










What if a budget came with just three buckets? The 50/30/20 rule divides monthly income among needs, wants and savings goals. It is quick enough to sketch on a napkin, though the napkin may need a few revisions once rent enters the conversation.
- Find the income figure. Start with a monthly amount after taxes and note how any paycheck deductions are handled.
- Sort the spending. Put essential costs, nonessential purchases and money for goals into separate groups.
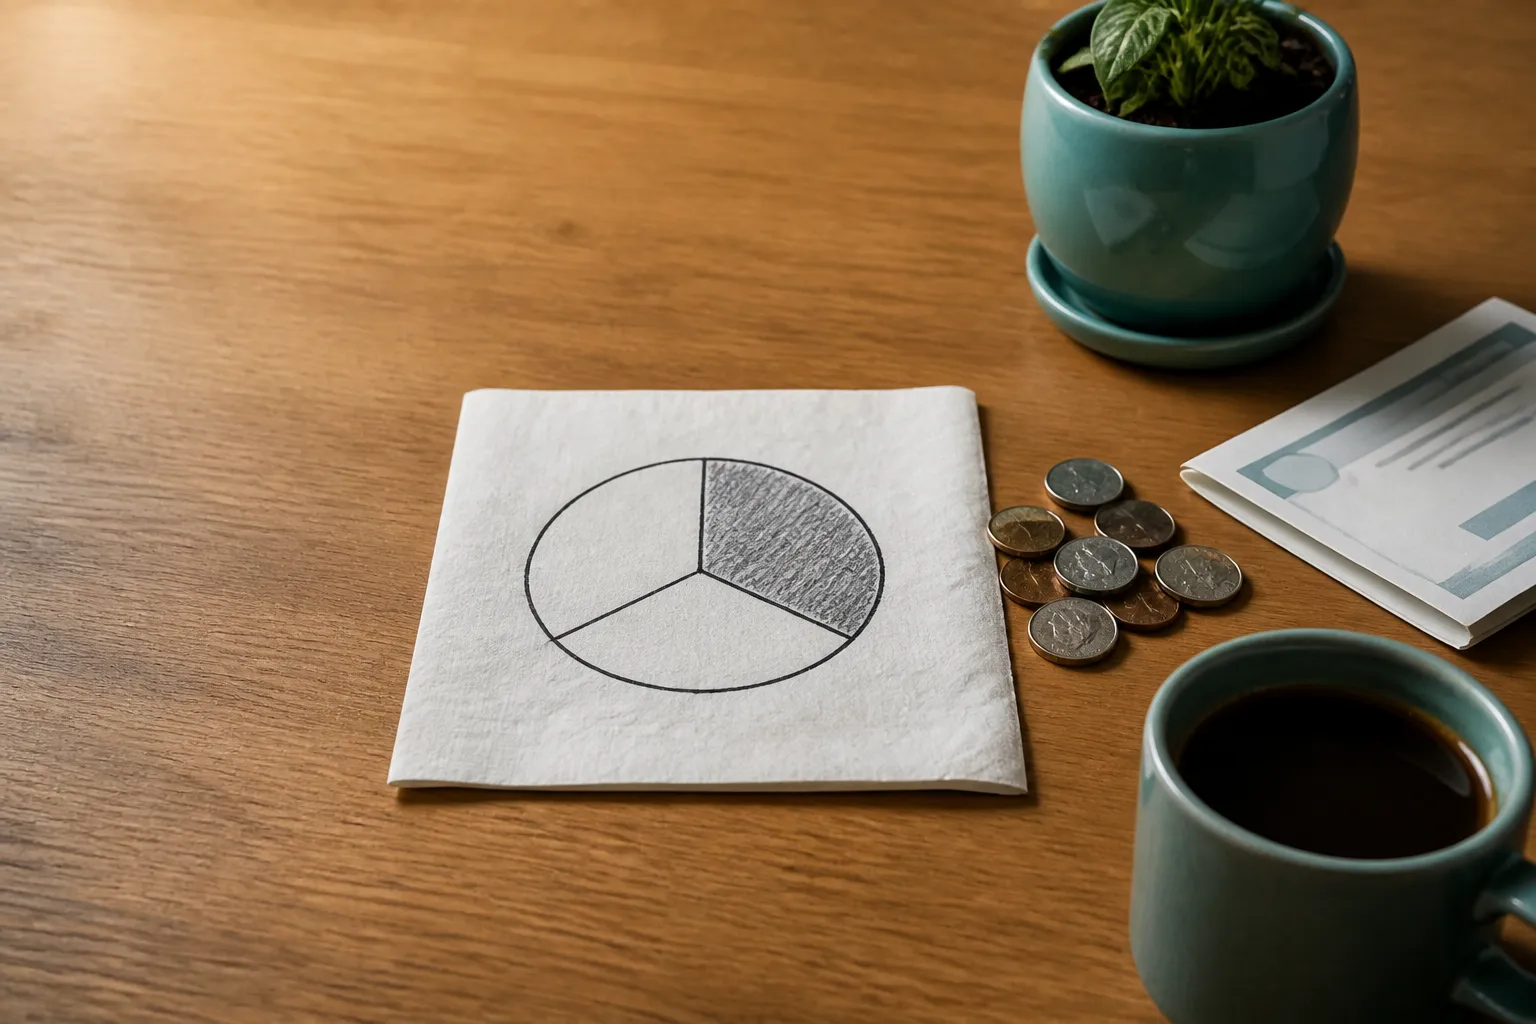
- Compare the totals. See how each group stacks up against 50%, 30% and 20% of the income figure.
- Adjust the picture. Treat the percentages as a reference point, not a test with a passing grade.
What goes in each bucket?
The rule assigns about 50% of after-tax income to needs, 30% to wants and 20% to savings and goals. Those numbers are a starting framework, not legal limits or a guarantee that a household can make the split work.
Needs are the costs of living and meeting basic obligations. They can include housing, groceries, utilities, transportation, childcare, medical care and minimum debt payments. Wants add comfort or enjoyment but are not essential, such as restaurant meals, entertainment, hobbies and vacations. Henrico County's explanation of the rule offers examples of these categories.
The savings and goals bucket can hold money for emergencies, retirement or a future purchase. Extra debt payments beyond the required minimum can go here, too. Keeping minimum payments in needs and extra payments in goals helps avoid counting the same dollars twice.
What does the math look like?
Suppose a household has $3,000 a month available after taxes. The rule would divide it into $1,500 for needs, $900 for wants and $600 for savings and goals. At $4,000, the same percentages produce $2,000, $1,200 and $800.
That is tidy arithmetic, not a portrait of every household. A family with high childcare costs or expensive rent may spend more than half its income on essentials before it buys a single movie ticket. Another household may have more room for savings. The numbers show what the rule asks for, not what any particular household can achieve.
How do you put the rule to work?
First, decide what income number the budget covers. A paycheck's deposit may be smaller than after-tax pay because the employer also withholds retirement contributions, insurance premiums or other amounts. One simple approach is to use the deposited amount and leave those payroll deductions outside the three buckets. If an after-tax deduction is added back into the income figure, it also needs a place in the budget. Otherwise, the comparison can count money as available without accounting for where it went.
Next, gather a month of transactions and regular bills. Sorting them may reveal more than the percentages do. Groceries generally belong under needs, while a restaurant dinner usually belongs under wants. A phone plan can sit between the two: basic service may be necessary, while extra features may be a want. The boundary depends on the expense and the household.
Monthly transactions can also miss costs that arrive less often. An annual fee, car repair or seasonal bill can make one month look very different from another. A budget can account for those costs by estimating their monthly share and setting it aside as a goal. MIT's budgeting guide describes the three-category approach and its flexibility.
Where does the rule run into trouble?
Steady income makes the percentages easier to use because the starting number is more predictable. With hourly, seasonal or irregular work, a strong month can make the available money look larger than it will be later. One possible approach is to build the comparison around a lower-earning month and treat higher earnings separately. The rule itself does not prescribe one method for variable pay.
Essential costs can also overwhelm the framework. If needs take 70% of income, the original 30% wants and 20% goals targets cannot both fit. A household could compare an adjusted split with its actual costs, but moving percentages on paper does not make rent or medical bills smaller. At very low incomes, even basic expenses may exceed available income. In that situation, local assistance programs or nonprofit credit counseling may be useful sources of information.
Couples and families can use the same buckets for a shared budget, but the categories still require decisions. For example, a shared grocery total may include both everyday staples and treats. The framework gives a household a common place to start that conversation; it does not settle it.
What questions does the rule leave open?
How much should go into an emergency fund? Should extra money go toward debt or retirement first? The 50/30/20 rule names the goals bucket but does not answer those questions. Once an emergency fund reaches a level a household has set, some of that money could go toward another goal, such as a home down payment.
High-interest debt may need a more detailed plan than the rule provides. The same is true of deciding how large a cash cushion should be or where to keep it. Those choices depend on circumstances the three percentages cannot capture.
Finally, a month that misses the suggested split is not a failed budget. It is information about income and costs for that period. The rule can make those numbers easier to see, but it does not establish typical household spending shares or prove that one budgeting method is better than another. This article is educational and is not personal financial, legal or tax advice.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


