










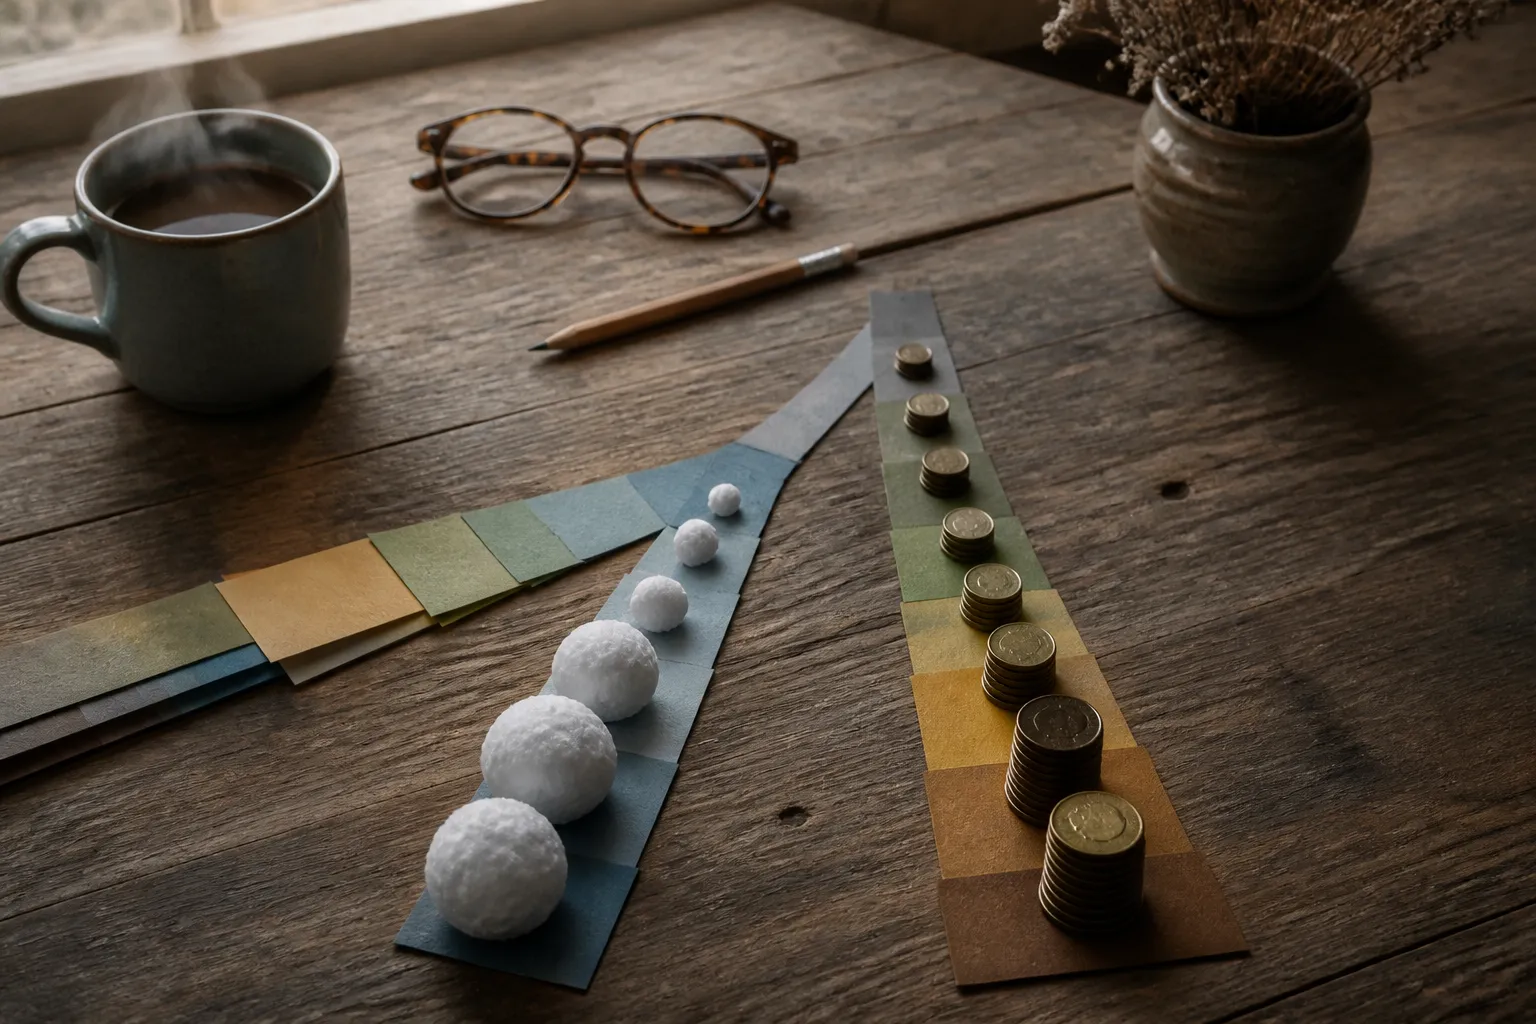
When you have several debts, deciding where to send an extra $50 can feel like choosing which leak to patch first. Two popular approaches offer a simple rule: the debt snowball starts with the smallest balance, while the debt avalanche starts with the highest interest rate. Both use the same payment routine, but they offer different kinds of progress.
What do the two methods have in common?
Both plans start with minimum payments on every debt. The minimum is the amount the lender requires for that billing period. Paying it by the due date helps avoid late fees and missed-payment marks. Any money available beyond those minimums goes to one target debt at a time.
Once the target is paid off, the money that was going to it rolls into the next debt. Think of it as moving the same shovel to a new pile rather than putting it away. The Consumer Financial Protection Bureau describes both methods as ways to make a plan for reducing debt.
Neither approach requires signing up for a program or paying a third party. Both do require room in the budget for extra payments. If new borrowing continues while old balances are being paid down, the process can take longer. And if there is no money left after necessary expenses and minimum payments, the first question may be how to make the budget workable, rather than which debt to target.
How does the debt snowball work?
The snowball puts debts in order from smallest balance to largest. After making all minimum payments, you send the extra money to the smallest balance, even if another debt has a higher interest rate. When the smallest is gone, its payment joins the extra payment going to the next smallest.
Why start small? An account paid in full is easy to see. That early finish can help someone stay engaged during a long payoff. The trade-off is that a larger debt with a higher rate may continue accumulating costly interest while smaller balances get attention. That can mean paying more interest overall than with the avalanche.
Imagine two debts: one has a $500 balance at 10%, and the other has a $2,000 balance at 24%. Under the snowball, the $500 debt is the first target. If its minimum payment is $25 and there is $100 extra in the monthly budget, the payment to that debt starts at $125. The other debt still gets its required minimum.
How does the debt avalanche work?
The avalanche reverses the sorting rule. It targets the debt with the highest annual percentage rate, or APR, first. APR expresses the cost of borrowing as a yearly rate and can include certain fees as well as interest. The National Foundation for Credit Counseling also calls this the highest-interest-rate or stacking method.
In the same example, the $2,000 debt at 24% is the avalanche target. If its minimum is $60, the $100 extra makes the starting payment $160. The $500 debt still gets its $25 minimum. Once the 24% debt is paid off, the amount that was going to it can be added to the payment on the remaining debt.
Focusing on the highest rate can reduce total interest costs compared with paying smaller balances first. But the first payoff may take a while if the highest-rate balance is large. In the example, the numbers show payment order, not a full payoff schedule. Actual costs and timing depend on the account terms, rate changes, payments and any new charges.
How can you choose and make a plan?
Start with a list of each debt, its current balance, APR, minimum payment and due date. Monthly statements and account agreements are places to check the numbers. Then look at income and necessary expenses to see how much extra money is realistically available. A target that leaves no room for ordinary bills is hard to keep.
Next, ask what will make the plan easier to follow. Someone who wants a quick visible finish may prefer the snowball. Someone focused on reducing interest costs may prefer the avalanche. If the smallest balance also has the highest rate, both methods point to the same first target.
A written goal can make either approach more concrete. For example, a person might plan to put an extra $100 toward the target debt each month for three months, then review the budget. Track payments and balances as they change, and check required minimums on each statement rather than assuming they will stay the same.
A smaller extra payment in a difficult month does not erase earlier progress. As University of Florida Extension notes, realistic goals and progress over perfection can make money plans easier to sustain. The plan can be adjusted when expenses or income change.
What if neither method fits right now?
Snowball and avalanche are not the only ways to address debt. A debt management plan is a separate arrangement in which a credit counselor helps combine payments on eligible debts into one monthly payment. Eligibility and terms vary. According to University of Wisconsin Extension, these plans can cover debts such as credit cards and personal loans, but generally do not cover car loans or student loans.
Before considering such a plan, useful questions include which debts are eligible, what fees apply, whether accounts must be closed and how payments are handled. Closing an account can affect credit, but no particular score change is guaranteed.
Some people also consider transferring a balance to an account with a temporary low or 0% interest rate. The temporary rate is only part of the picture. Fees, eligibility, the length of the offer and the rate afterward matter too. Taking on new debt or moving a balance does not by itself make the amount owed disappear.
This guide is educational, not personal financial, legal or tax advice. If minimum payments are already difficult to cover, a qualified professional or credit counselor can help explain options for the particular situation.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


