










Holiday spending rarely arrives as one neat bill. Gifts, travel, food and hosting can show up as separate purchases, then gather into a total that is hard to remember. A budget made before shopping starts gives those costs a place to land, and gives you a number to check before buying.
Start with the expenses that already fill a typical month. Then add the season’s extras, such as a trip to visit family or groceries for a gathering. The Consumer Financial Protection Bureau (CFPB) lays out this order in its holiday spending plan: know the regular costs, estimate the seasonal ones, and plan how to cover them.
A 2025 AICPA and Harris Poll survey found that 42% of holiday shoppers and travelers expected to spend more than $1,000 on the season. Half expected to spend at or below that amount, while 8% were unsure. Those figures are a snapshot, not a target. Your own ceiling should come from your income and expenses, not someone else’s holiday total.
Write your estimate somewhere you can check it. A note on paper or a simple digital list works. The point is to make the budget visible before the first purchase, rather than trying to reconstruct it from a stack of receipts later.
Build the budget before the shopping list grows
Give the season a total limit, then divide it into categories such as gifts, travel, food and hosting. Include the small costs that are easy to overlook, like wrapping supplies or an extra meal on a travel day. A budget that leaves out predictable costs is like a suitcase with no room for shoes: the missing space does not make the shoes disappear.
Once you have a rough total, compare it with what you can set aside from income before the holidays. The CFPB’s approach is to estimate costs first and save toward them, rather than treating borrowing as the default way to fill a gap. If the total is larger than the amount you can put aside, revisit the categories and adjust the plan before shopping begins.
That may mean setting a lower overall ceiling or changing what is included in the season’s plans. There is no universal “right” holiday budget. The useful number is one that accounts for regular bills and does not rely on money you are not sure you will have.
Give each gift a limit, then check the list
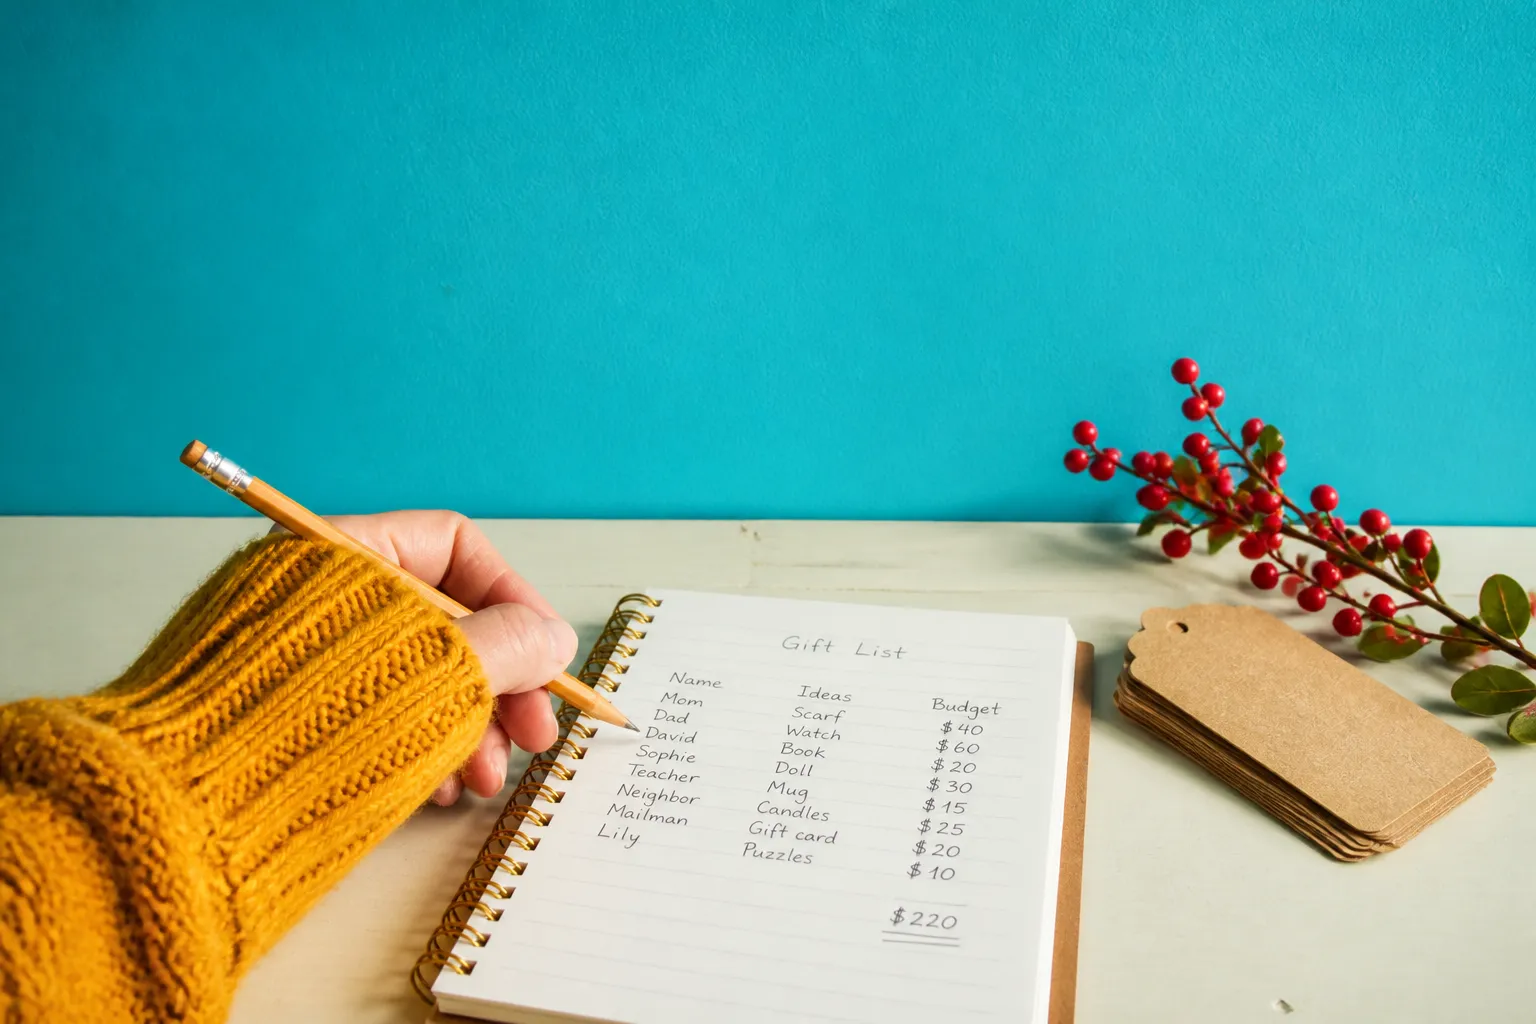
Make a list of the people you plan to buy for and assign a spending limit to each name. Add those amounts together and compare the sum with your gift budget. This turns “I’ll find something for everyone” into a set of choices you can review while there is still time to change them.
A personal rule can help slow down unplanned purchases. For example, you might decide to buy only items on the list, or wait a day before purchasing something that was not planned. The CFPB suggests using a checked gift list and personal rules to reduce impulse spending. A pause will not make every tempting item less tempting, but it gives you a moment to see whether it fits the plan.
Check the list again before the final round of shopping. If the total has crept above the limit, decide what to change before making more purchases. The AICPA’s holiday debt guidance also suggests saving from income over time. It gives examples of monthly contributions such as $20, $50 or $100, depending on what fits. Those are examples, not required amounts. If there is little room after regular expenses, the sources do not offer a one-size-fits-all savings fix.
Know how you will pay before checkout
Payment methods can make a purchase feel more or less visible. In the 2025 AICPA and Harris Poll survey, 79% of holiday spenders said they planned to use a credit card, and 52% did not expect to pay the full balance when the bill arrived. A separate National Foundation for Credit Counseling (NFCC) article cites Federal Reserve survey data showing that credit cards are the most popular payment method among U.S. adults.
The NFCC also reports that people spend about 18% more with credit cards than with cash. Cash makes the amount leaving your hands easy to see. Digital payments can feel less tangible because no bills or coins change hands. This does not mean one payment method suits everyone. It does mean the method is worth including in the plan, alongside the price.
Buy Now, Pay Later, or BNPL, lets a shopper split a purchase into four or fewer payments. The CFPB warns that some BNPL loans may lack protections that apply to other types of credit and may encourage spending beyond the original plan. Before using one, check the provider’s terms for late fees and what happens to remaining payments if an item is returned. A return may not automatically end the loan. The CFPB explains these points in its guide to BNPL purchases.
If holiday debt is already on the books
If a holiday balance remains, estimate a monthly payment and how long repayment could take at that amount. That timeline makes the balance easier to understand than a single number on a statement. The AICPA’s guidance suggests considering the highest-interest debt first when there is more than one balance. Your account statements and terms show your own rates; the sources here do not provide a typical rate to use as a comparison.
Some households set a tighter discretionary budget in January or February to direct more money toward repayment. The AICPA calls this a “holiday recovery” month. In the 2025 survey, 17% of people expecting holiday debt said it would take more than six months to pay off. Thirty percent planned to use a tax refund for repayment, but a refund is not guaranteed, so it is not the same as a payment plan already built around available income.
Credit counselor and consumer-protection resources may help people understand their options. The sources cited here do not cover every repayment situation or provide a personalized plan. They do support a basic first step: put the balance, possible monthly payment and estimated payoff time in view.
Use a mid-year check to catch drift early
A holiday plan does not have to wait until autumn. The NFCC describes a mid-year financial checkup as a chance to review spending, debt, savings and credit reports before the holiday season. That leaves time to adjust a budget or start setting money aside, rather than making every decision in the busiest shopping weeks.
Warning signs can be simple. A purchase may require little or nothing at checkout but create payments later. The shopping list may keep growing without the budget changing. Or you may already expect to carry a card balance after the bill arrives. In the AICPA survey, 39% of holiday spenders said they had regretted overspending.
Before a purchase, check three things: Does it fit the limit? Can it be covered by money already set aside? If it requires borrowing, how long could repayment take at a monthly amount that fits the budget? Those questions will not remove every seasonal expense. They can keep one unplanned purchase from quietly becoming next year’s first bill. The NFCC’s mid-year checkup overview offers more context on the review.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


