










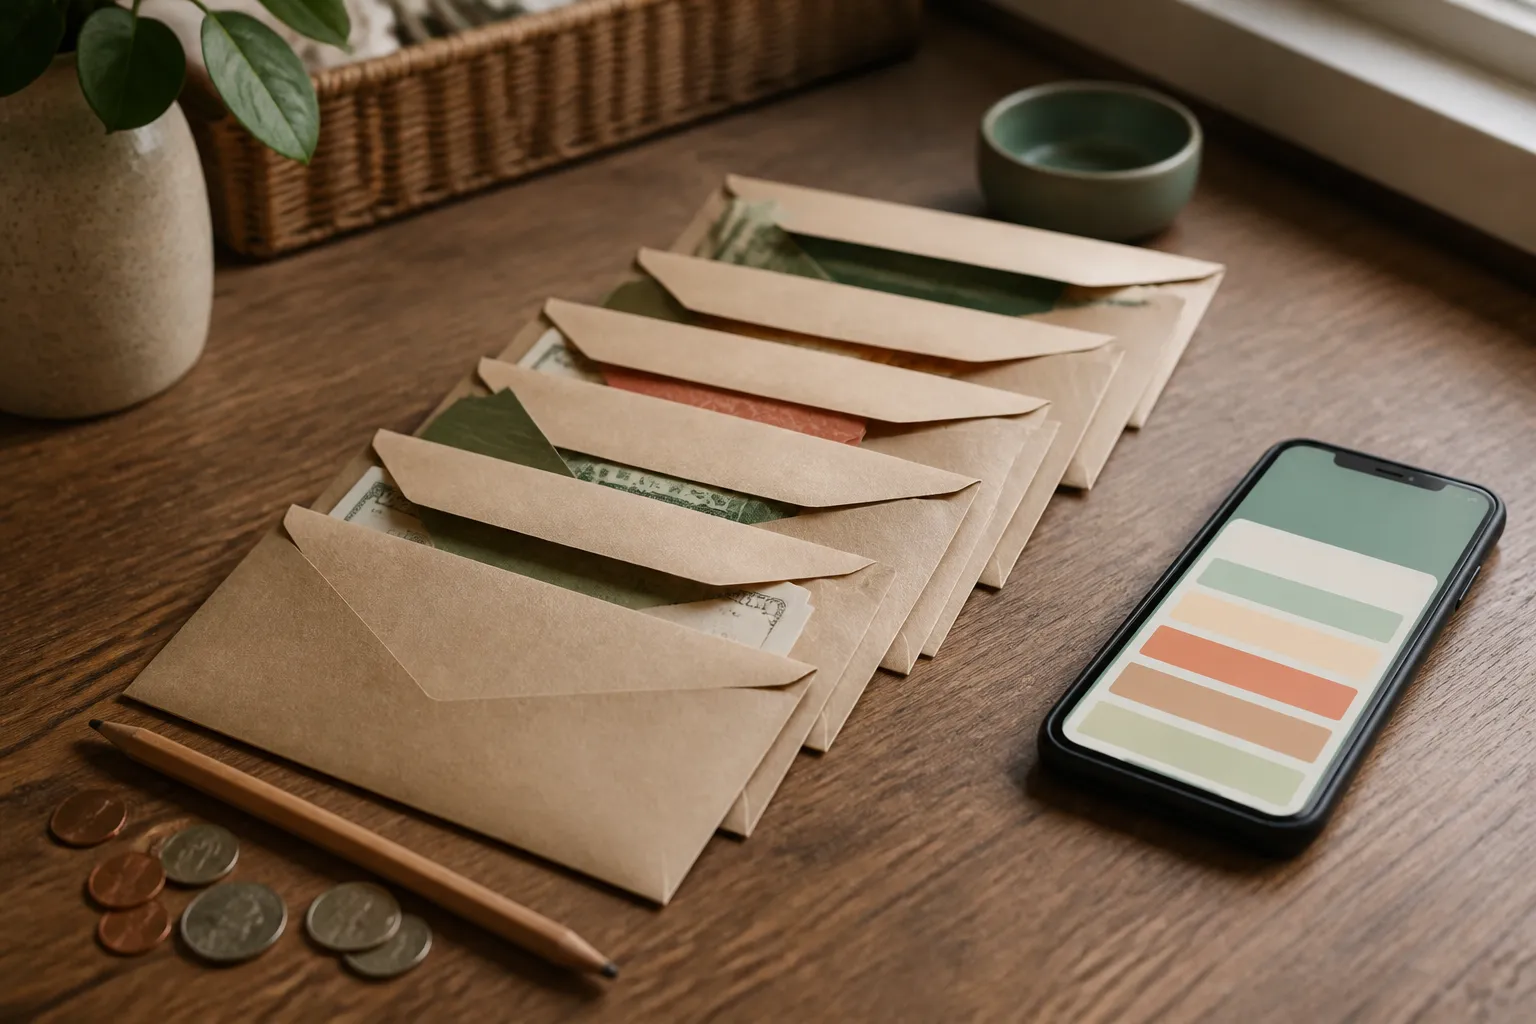
How much of your checking balance is actually available for dinner out? The envelope method gives that money a job before you spend it. Traditionally, that means cash in labeled paper envelopes. A digital version keeps the same idea, without asking your grocery money to live in a desk drawer.
What is the envelope method?
Envelope budgeting divides available money into categories with spending limits. If the grocery envelope holds $100, that is the amount available for groceries until you add more. When an envelope runs out, spending in that category pauses, or you make a deliberate decision to move money from another category.
The paper version is also called cash stuffing. It is especially useful for seeing limits on variable expenses, the costs that change with your choices or needs. Groceries, gas, entertainment and dining out are common examples. Rent and other fixed bills can sit outside the cash envelopes and be paid as usual. A guide to the method describes the basic rule: once a category is empty, there is no more spending from it until it is funded again.
How does the cash version work?
Start with the whole budget, not just the fun envelopes. Income has to cover fixed bills and other priorities as well as the categories you plan to manage with cash. These are the basic steps:
- List expenses. Include fixed costs such as rent, insurance and car payments, then variable costs. Past utility bills can help with an estimate for bills that change by season.
- Set category limits. Look at what you have actually spent, especially on categories that tend to run over. A limit needs to fit the money available and the period it has to cover.
- Pay fixed bills and fill envelopes. Fixed bills can be paid by check, debit card or online. Withdraw the amount assigned to cash categories and divide it among labeled envelopes.
- Track and review. Check what remains as you spend. At the end of the month, compare your limits with what happened and adjust the next plan if needed.
How do you turn envelopes into a digital system?
Imagine the paper envelopes as labels rather than containers. The money may stay in an account while a spreadsheet or virtual category records how much is assigned to each purpose. Some people use separate accounts instead. Either way, the category balance is a spending limit, not extra money on top of the account balance.
- Choose your categories. Start with a few variable expenses you want to track, such as groceries and dining out. Keep fixed bills in the plan too, even if they do not need separate virtual envelopes.
- Assign money you have available. Record an amount for each category or transfer it to a separate account. Match the amounts to your pay schedule. For example, a $200 monthly grocery limit could be funded with $100 from each of two paychecks, if the timing works for the household.
- Record purchases against the right category. A $35 grocery purchase reduces a $200 grocery envelope to $165. Check the category before the next purchase, and account for transactions that have not yet appeared in your balance.
- Make changes visible. If groceries need another $20, moving $20 from dining out changes both limits. Recording the move prevents the same dollars from being counted twice.
Some digital systems update transactions as they arrive, while a simple spreadsheet requires manual entries. A digital envelope overview describes using separate accounts or virtual categories to make balances easier to check. Availability and timing of updates depend on the setup, so a displayed balance is worth checking against pending purchases.
What changes when you use cards instead of cash?
Cash has a built-in stop sign: an empty envelope is hard to miss. Digital money is less tactile. An account may still have a balance even when the amount assigned to dining out is gone, so the category record matters. It helps distinguish money that looks available from money already set aside for another bill.
Credit cards add another layer. A purchase can use up a category limit now, while the card payment comes due later. A digital record needs to distinguish the spending decision from the eventual payment so the same purchase is not counted twice. The sources for this article do not explain credit card balances or debt repayment in detail, so the envelope label alone should not be mistaken for a complete debt plan.
Which version fits your daily life?
Paper can make the limit visible without a screen, but carrying cash has risks. Withdrawing it may mean an ATM fee or a trip to a bank, and cash is awkward for online payments. Paying in cash can also mean giving up rewards available on some credit cards. Digital categories are easier to use for card and online purchases, but they depend on accurate records and a system you will check.
Before choosing a digital setup, ask where the money will be held, how transactions are recorded and what fees or transfer terms apply. The sources do not provide specific fees or a list of available account features. They also do not cover account security in detail, an important consideration when using any digital money tool.
What should you review at the end of the month?
Look for categories that repeatedly run short and ask why. Was the limit unrealistic, did prices change, or did an unexpected purchase belong somewhere else? A budget can be revised. Moving money between categories is a trade-off, so the useful question is what must get less when another category gets more.
Also look beyond the monthly envelopes. Annual insurance premiums, tax bills, debt payments and emergency savings may need space in the broader plan. The sources do not explain in detail how to fit those items into the method. If money is too tight to cover bills, the Consumer Financial Protection Bureau has tools for thinking through bill payments.
Envelope budgeting is one way to organize spending, not a proven winner over every other approach. The available sources do not compare long-term results. Other options include the 50/30/20 approach, which groups spending into needs, wants and savings, and zero-based budgeting, which assigns each dollar a purpose. The best test of a system is whether its record gives you a clear picture you can use, and whether you can keep it current.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


