










How much should you set aside for medical care before the year starts? An FSA or HSA can help you pay certain health expenses with money set aside before tax, but the accounts have different rules. A useful budget starts with two questions: Are you eligible, and how predictable are your costs?
What are an FSA and an HSA?
A flexible spending account, or FSA, is an employer arrangement for paying many out-of-pocket medical expenses with pre-tax dollars. It is generally connected to your job. Your employer decides whether to contribute to the account, and is not required to add money. Check your benefits materials to see whether an FSA is offered and how enrollment works. HealthCare.gov explains how job-based FSAs work.
A health savings account, or HSA, is a savings account for people enrolled in an HSA-eligible health plan. After enrolling in an eligible plan, you open the account through a financial institution, such as a bank or credit union. Not every plan qualifies. HealthCare.gov describes HSA eligibility and setup. An FSA cannot be used with a Marketplace plan, so check the type of coverage you have before comparing accounts.
Which account fits the way you spend?
An FSA can suit costs you expect to pay during the plan year, such as regular prescription expenses, copayments, or medical supplies. Think of it like packing for a trip: a short list of known needs makes it easier to avoid bringing too much. You choose an amount ahead of time, so a rough estimate based on past bills and known appointments can help you avoid setting aside more than you can use.
An HSA can suit someone who wants to save for qualified health expenses over a longer period. Money you do not spend can remain in the account from year to year, according to Vanguard's overview of FSA and HSA differences. Health costs can also be a significant part of retirement planning. Still, eligibility, contributions, and what happens when you change jobs or plans are all worth checking before you enroll. Do not assume the accounts have the same rules just because both can use pre-tax money.
If you already contribute to a 401(k) or IRA, an HSA may be another tax-advantaged savings option when you qualify. That does not make it an automatic fit. Compare when you can use the money, what expenses qualify, and whether account fees affect the amount you keep. The IRS publishes information about these accounts in Publication 969. Check current IRS guidance for contribution limits and withdrawal rules rather than relying on an old figure.
How much should you put in, and when can you spend it?
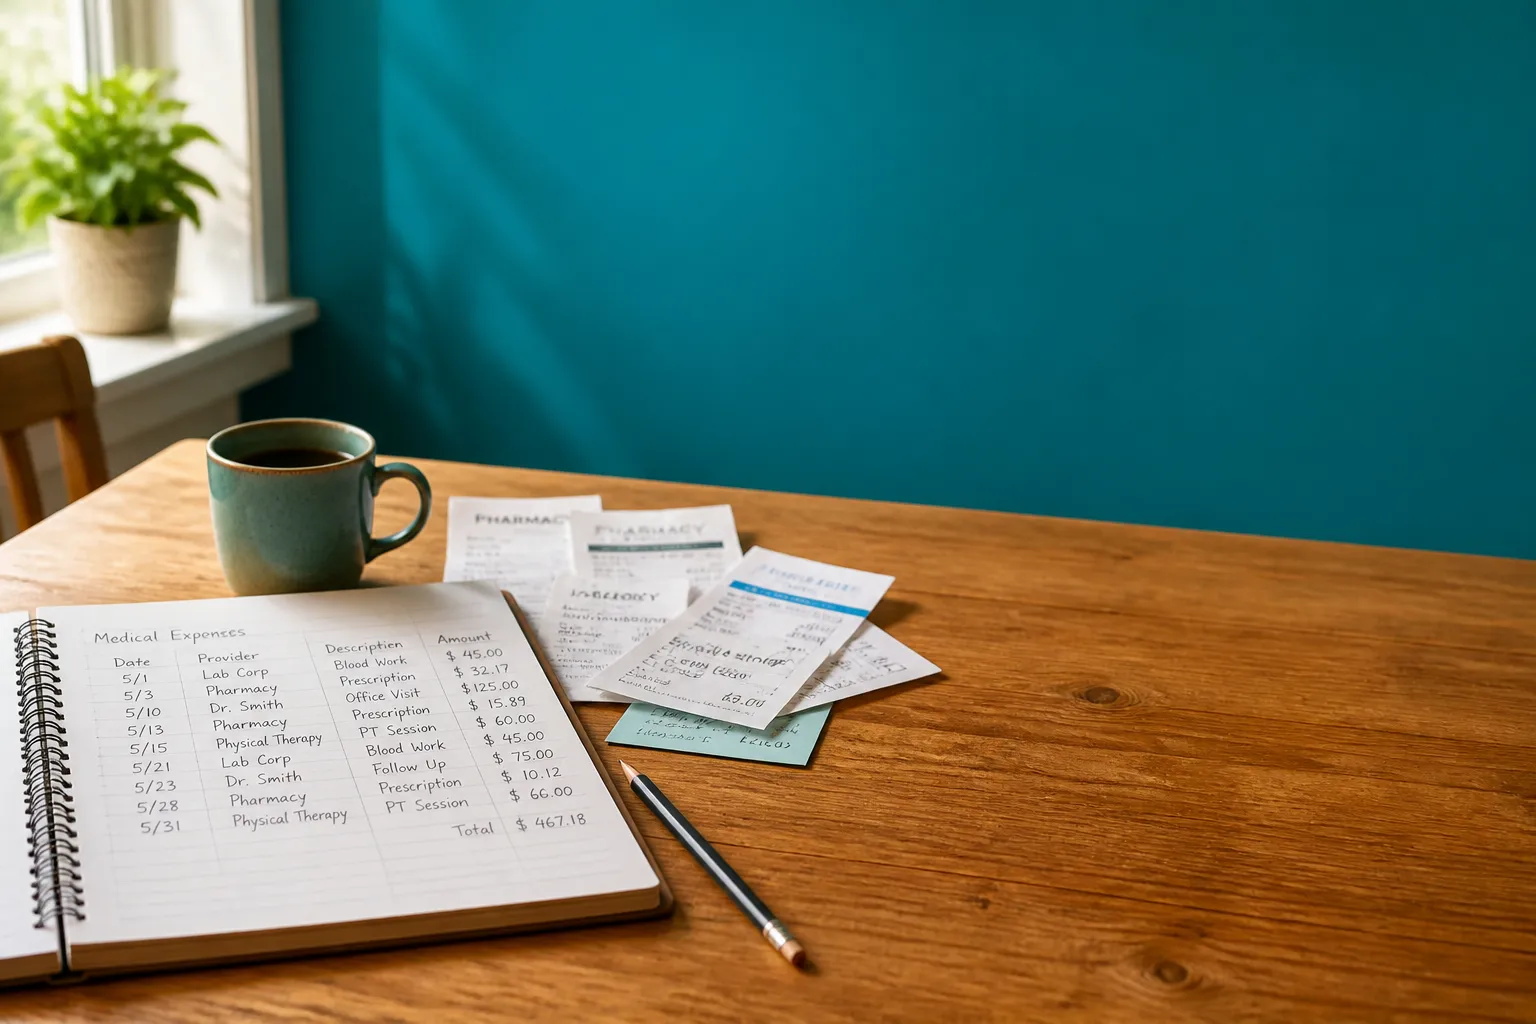
Start with a simple budget exercise: look at last year's medical and dental bills, then list costs you already expect this year. Include regular prescriptions, planned appointments, deductibles, and copayments. Separate known costs from guesses. If you are paid every two weeks, for example, divide a planned annual contribution across 26 paychecks to see what it would mean for each paycheck. That is a budgeting estimate, not a reason to contribute more than you can manage.
HealthCare.gov lists an FSA contribution limit of $3,300 per year per employer. A spouse can also contribute up to $3,300 through their own employer's FSA if married. Confirm the current limit and plan-year details with your employer. FSAs often have a use-it-or-lose-it rule, but the employer may offer either an extra 2.5 months to spend leftover money or a carryover of up to $640 into the next plan year. The plan cannot offer both options. Ask which rule applies before you choose an amount. HealthCare.gov's FSA glossary describes these options.
For an HSA, verify the current contribution limit and rules with the IRS. The limit can depend on details that are not covered by a general comparison, so avoid treating a prior year's number as current. Your employer or plan administrator can also explain how contributions are made and what happens if your coverage changes.
What counts as an eligible expense?
FSA funds can cover many qualifying medical and dental expenses for you, your spouse if you are married, and your dependents. Examples include deductibles, copayments, prescription medicines, insulin, and supplies such as bandages or blood sugar test kits. Over-the-counter medicine generally needs a doctor's prescription to qualify under the cited guidance. Insurance premiums are not an eligible FSA expense.
HSA funds can generally pay for qualified medical costs such as deductibles, copayments, and coinsurance, but generally cannot pay insurance premiums. The exact expense matters, so check the IRS list of generally permitted medical and dental expenses before paying. For an FSA reimbursement, keep proof of the expense and documentation showing the plan has not already covered it. A receipt is a small piece of paper that can save a larger administrative headache.
What should you check before enrolling?
Ask your employer which FSA options and deadlines apply, including whether the plan offers a carryover or an extra spending period. Ask how reimbursement works and what records you need. If you are considering an HSA, confirm that your health plan is HSA-eligible, then compare the account's fees and basic features. Opening, closing, and monthly maintenance fees can reduce the balance over time. Also check how you can add money and whether the account includes features such as online access or a debit card.
Finally, ask what happens to the money if you leave your job or change health plans. The rules can differ by account and plan, and they are not captured by a simple FSA-versus-HSA label. Before setting a contribution, use your own bill history to make a cautious estimate, then confirm the details with your employer, plan administrator, and the IRS. This article is educational and is not personal financial, legal, or tax advice.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


