










You handed over a check to secure a start date, purchase custom materials, or lock in an estimate. Then the promised start date passes, the phone calls go straight to voicemail, and the crew never arrives. The contractor has your cash and you have an empty calendar.
A disappearing contractor is not just a frustrating delay. In many cases, it is a deliberate fraud tactic designed to exploit the gap between signing a deal and swinging a hammer. Recovering that money requires shifting immediately from informal negotiations to formal documentation.
Why deposit scams happen and how they usually unfold
Home improvement fraud follows well-worn patterns. According to warnings from the Better Business Bureau on home improvement scams, fly-by-night operators and predatory individuals frequently impersonate legitimate, established businesses. They extract an upfront payment and then vanish before turning a single screw, or they drop off a small pile of boards, perform an hour of superficial demolition, and never return.
These schemes often start with unsolicited contact. A salesperson knocks on your door claiming to have leftover asphalt from a paving job down the road, or a targeted advertisement pops up on social media offering heavily discounted roofing repairs. The pressure is immediate. You are told the discount is good only for today, or that weather damage requires immediate intervention before your home suffers structural ruin. The BBB’s 2024 Scam Tracker Risk Report found home improvement scams ranked as the third riskiest scam category for consumers aged 65 and older, largely driven by these aggressive tactics.
Once on site, the operator insists on cash or a personal check made out to an individual rather than an incorporated entity. Some will even claim a check failed to clear and demand a second payment. Following natural disasters, scammers routinely attempt to persuade homeowners into signing over insurance benefit checks directly. Any agreement that asks you to transfer control of your insurance proceeds before work begins is an enormous warning sign.
Your first steps: gather the paper trail
Before you call an attorney or contact law enforcement, you need to assemble your evidence. The Georgia Attorney General’s Consumer Protection Division notes that the foundation of any complaint, bond claim, or legal action rests entirely on objective records. In one case documented by Georgia regulators, a consumer paid a $3,900 deposit on a $5,400 contract, only for the worker to pocket the deposit and never begin.
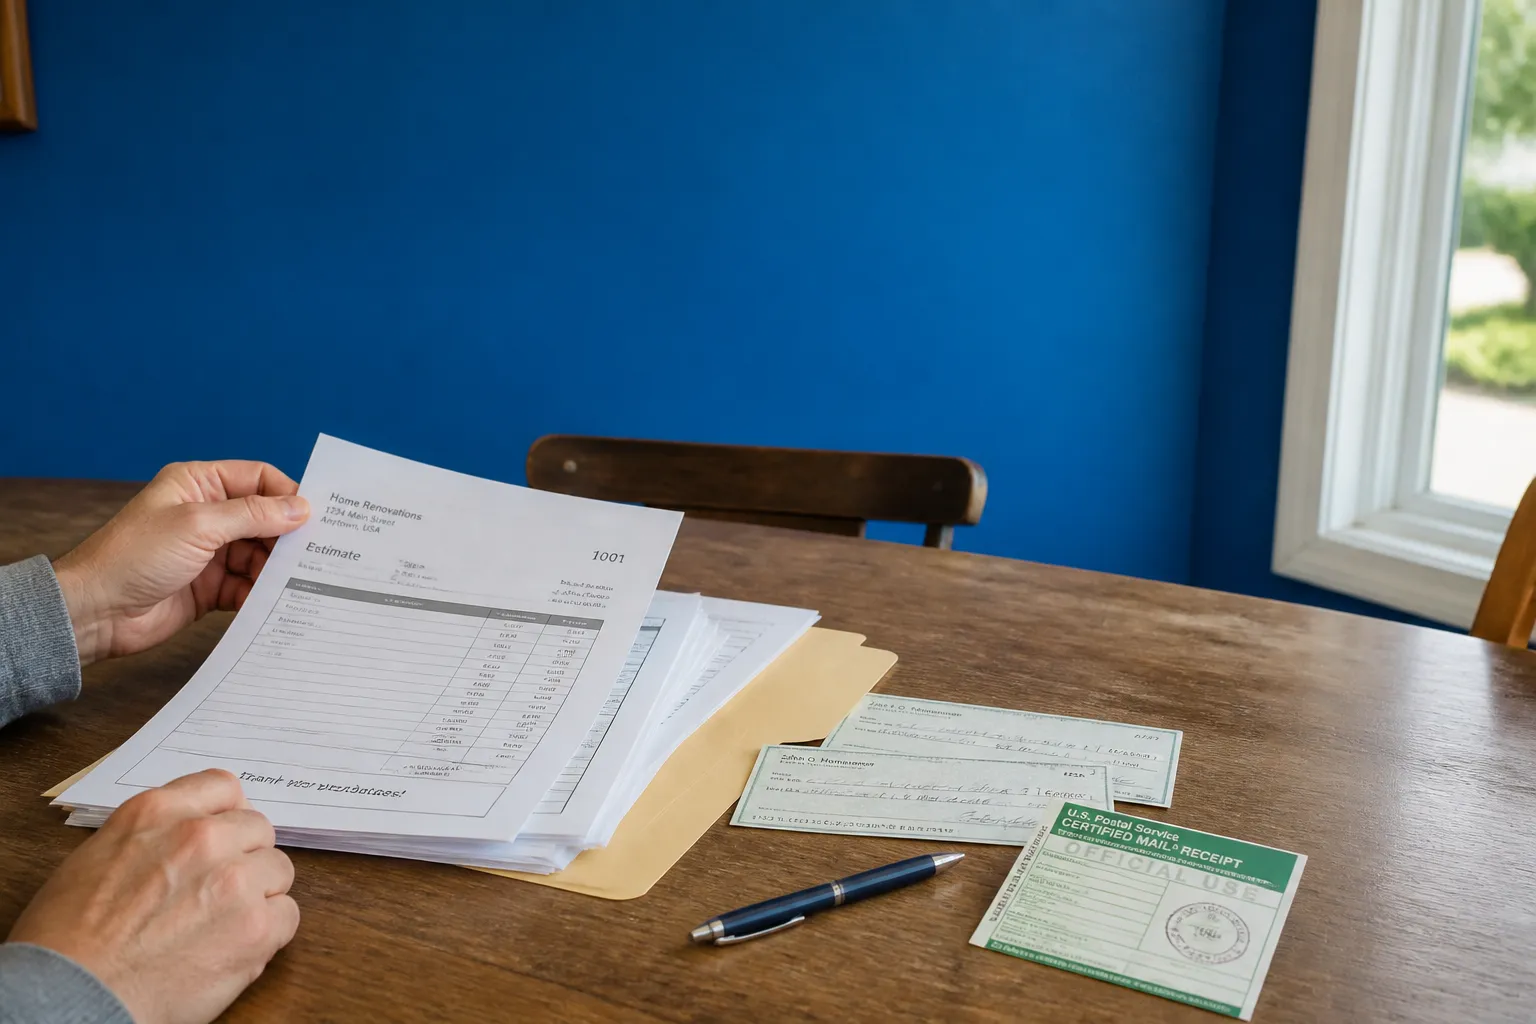
Create a dedicated file. Collect the original written proposal, the signed contract, every change order, proof of payment, and copies of any building permits. Print out text message exchanges, call logs, and emails with timestamps showing your attempts to confirm a start date. If the contractor abandoned partial work on your property, take high-resolution, dated photographs from multiple angles.
Examine the written agreement closely. Note whether it contains specific start and completion dates, a stated refund schedule, or formal clauses covering contractor default and no-show conditions. Even if your contract lacks these clauses, or if your arrangement was built on a verbal agreement, you still retain statutory consumer protection rights.
Your payment method dictates your immediate options. If you paid your deposit using a credit card, federal rules and billing dispute guidelines generally allow you roughly 60 days from the date the charge appears on your statement to dispute the billing error. Debit card transactions and paper checks carry far fewer automatic reversal protections, so you must contact your financial institution promptly to explore what stop-payment or fraud reporting options exist.
Send a demand letter you can prove was delivered
Informal phone calls and text messages are easy to ignore. A formal written demand letter sent via certified mail with a return receipt requested changes the dynamic. It creates a verified date stamp proving the contractor received your grievance.
Your demand letter should be direct, factual, and devoid of emotional language. State the date the contract was executed, the precise amount paid as a deposit, and the obligations the contractor failed to meet. Clearly outline the remedy you require, such as a full refund of the deposit or completion of specific deliverables, and assign a firm, reasonable deadline to respond, typically ten business days from receipt.
Regulatory agencies, licensing boards, and small claims courts expect to see that you provided the business a clear opportunity to cure the breach before initiating formal actions. Keep an exact duplicate of the signed letter alongside the post office receipt and the green tracking card once it returns to you.
Recovery channels and how they fit together
Payment dysfunction takes a massive toll on the home services sector. Analysis cited by Build Safe Escrow on disappeared contractors noted that payment dysfunction added an estimated $280 billion in costs across the domestic construction industry in 2024 alone. Homeowners left with abandoned projects must frequently navigate multiple administrative and legal avenues simultaneously.
- State Licensing Board Complaints: If the worker holds a professional license, your state licensing board can investigate professional misconduct, levy administrative fines, or suspend credentials.
- Surety Bond Claims: Licensed contractors are frequently required to post a surety bond. A bond functions like an insurance policy protecting consumers against financial malfeasance. Many jurisdictions require you to give written notice to the contractor of your intent to file against their bond before submitting the claim.
- State Guaranty Funds: Some state agencies maintain recovery or guaranty funds financed through contractor licensing fees. These funds provide financial reimbursement to injured consumers. However, many funds require you to obtain an unsatisfied civil court judgment against the contractor before releasing any funds, and statutory payout caps vary widely.
- Small Claims Court: When the lost deposit falls beneath your state’s small claims monetary cap, this forum offers a streamlined, relatively inexpensive mechanism to secure a legal judgment without needing private legal counsel.
Do not wait for one administrative channel to close before starting another. In most jurisdictions, submitting a complaint to an administrative board does not prevent you from preparing a small claims lawsuit. Always confirm with the respective court clerk or agency office that filing parallel claims does not conflict with local filing rules.
Finding the right agency and reporting the scam
Locating the proper oversight entity can feel confusing because regulatory authority is split among local, county, and state agencies. Your state attorney general’s consumer protection bureau serves as the natural clearinghouse. They can direct you to the specific trade board handling residential contractors, electrical trades, or plumbing specialists.
At the federal level, the Federal Trade Commission provides guidance on avoiding home improvement scams. Submitting an intake report through the FTC helps federal and state authorities track deceptive patterns, shut down regional networks, and build consumer enforcement actions. While federal agencies do not act as your private collection attorney, your report feeds the regulatory databases that regional task forces monitor.
Questions to ask before you pay the next contractor
Protecting yourself on future projects requires tightening your payment terms and screening protocols before signing any paperwork. Never rely on handshakes or marketing claims alone.
- Does the contract clearly define the scope of work, start date, substantial completion date, and an explicit refund policy if work does not begin?
- Are payment milestones tied to verifiable progress rather than arbitrary calendar dates, with the initial deposit kept as low as permissible under local regulations?
- Can you pay by a method that provides established dispute mechanisms, rather than irrecoverable cash, wire transfers, or direct peer-to-peer digital transfers?
- Did you independently confirm the status of the contractor’s license, general liability coverage, and active surety bond directly with your local licensing board?
- Does the upfront deposit exceed the limit you could comfortably recover within your jurisdiction’s small claims court system if the project fails?
Walking away from high-pressure sales pitches and insisting on balanced contract language is the most reliable defense against project abandonment. When an operator demands a large cash deposit to buy materials before setting foot on your property, treat that request as an immediate signal to find another provider.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


