










A payday on the calendar does not tell you exactly when a direct deposit will appear in your account. Your employer has to send the payment, the banking system has to process it, and your bank or credit union has to make the money available. Those steps explain why one paycheck may show up early while another appears later than expected. The useful date to check is when you can use the funds, not just when a deposit appears as pending.
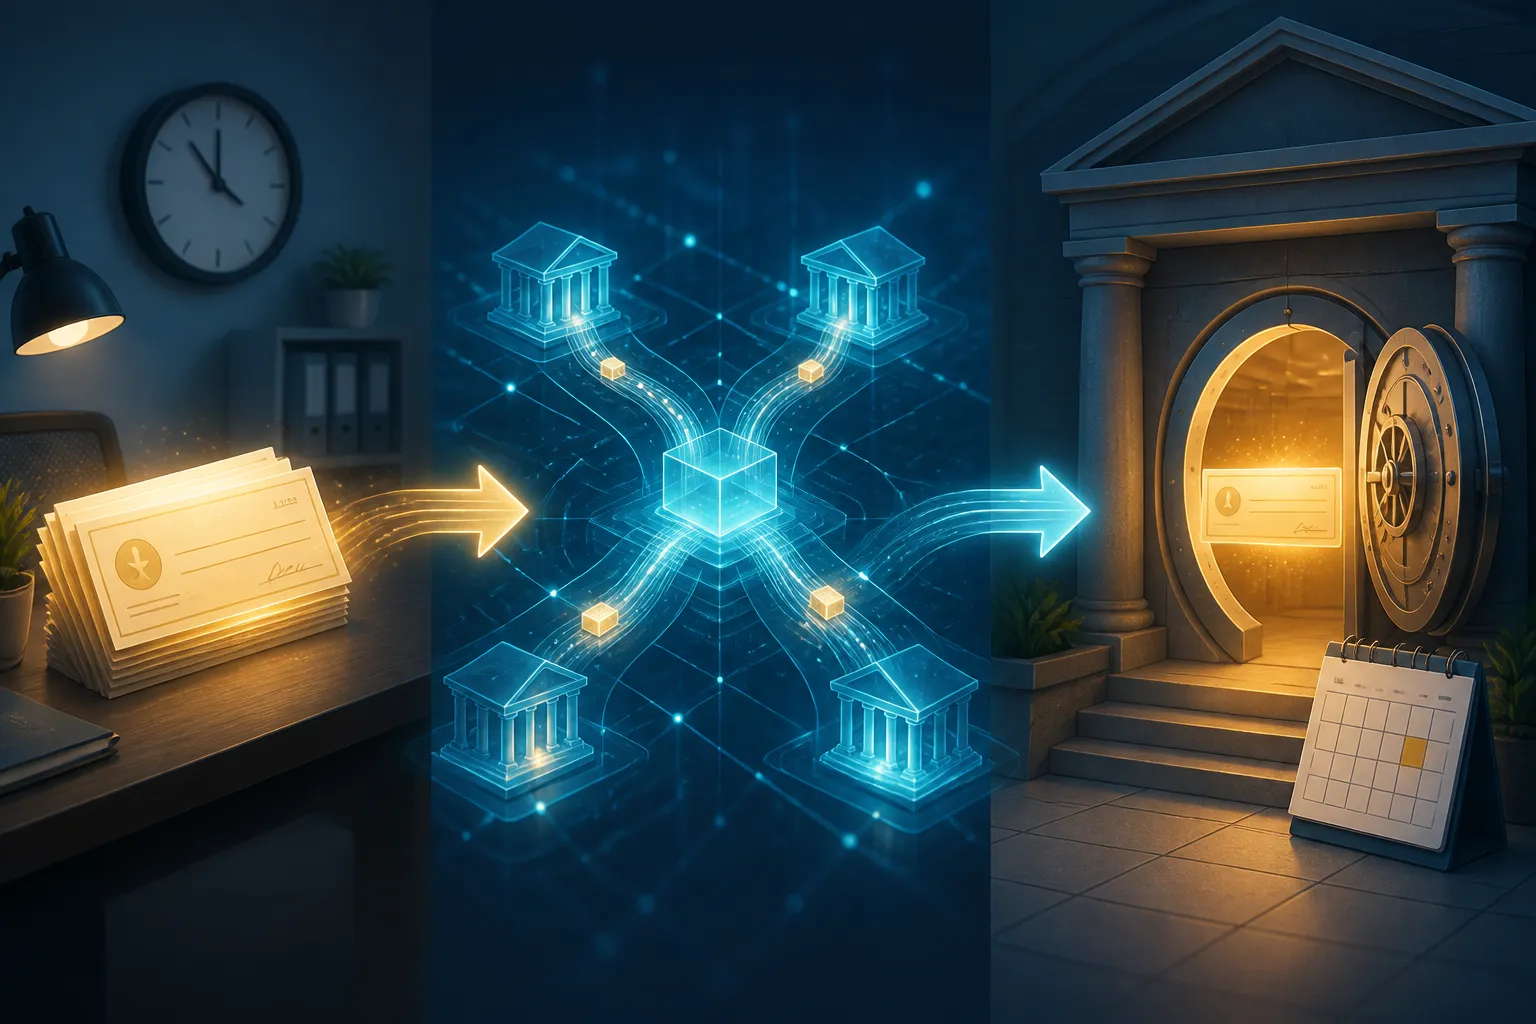
How a paycheck gets to your account
Most direct deposits travel through the Automated Clearing House, or ACH. ACH is an electronic payment network that moves money between banks and credit unions. It handles paycheck deposits as well as recurring debits, such as bill payments, according to the Consumer Financial Protection Bureau.
Sending a payroll payment is not the same as making it available to spend. The payment passes through processing before the receiving bank can provide access to the funds. Some ACH payments can settle on the same business day, while others take longer. The time your employer or payroll administrator submits a payment also matters, but there is no single submission time that applies to every workplace. If your pay date has changed unexpectedly, that is a question for payroll as well as your bank.
Why a deposit can appear early
Many banks and credit unions make payroll deposits available as soon as they receive them. That can mean the money is usable before the payday printed on a pay stub. Early access depends on when the payment reaches the institution and on its policy for your account. A deposit that arrived early last time does not establish a new payday for the next one.
There is an important contrast between early availability and a direct deposit advance. With early availability, the institution gives you access to an incoming deposit. A direct deposit advance is a loan that is repaid from a later deposit. The CFPB warns that advances may carry high fees. The account terms should make clear which arrangement applies and, for an advance, how repayment works.
Why the same payday can feel late
The receiving bank’s clock starts when it receives the electronic payment, not when you expect your employer to send it. Under the availability rule described by the CFPB, banks and credit unions must make electronic deposits, including ACH deposits, available no later than the next business day after receipt. Many release payroll deposits sooner. A payment received later than usual may still meet that rule even if it misses the time you normally check your balance.
Business days matter. Weekends and federal holidays can interrupt the usual processing rhythm, so a Friday or holiday-period payment deserves a closer look at the dates involved. Institutions also use cut-off times to decide when certain deposits count as received. CFPB guidance says a cut-off for deposits at a physical location can be no earlier than 2:00 p.m., and one at an ATM or elsewhere can be no earlier than noon. Those branch and ATM cut-offs do not tell you when an incoming payroll ACH file arrived. For that, ask your bank when it received the deposit and when it made the funds available.
Which holds belong in this conversation
A delayed direct deposit and a held check can look similar in an account balance, but they may follow different rules. The next-business-day standard applies to electronic deposits. Check availability depends on the type of check and how it was deposited. A check submitted through a mobile app, for example, may have a different timetable from one handed to a teller. If the missing money came from a check rather than payroll ACH, ask about the check policy instead of assuming the direct deposit rule applies.
The CFPB also describes circumstances in which an institution may hold certain deposits longer, including a newly opened account or one that has been overdrawn repeatedly. Suspected fraud, a concern about whether a check will be paid, or an emergency can affect availability too. The reason matters: a payroll payment that has not reached the bank cannot be released by the bank, while a deposit the bank has received may be subject to its availability policy. Ask which situation applies to the transaction you are tracking.
What to ask when the timing changes
Start with the account record. Is the deposit pending, posted, or available to withdraw? Those terms can mark different stages. Ask the bank or credit union when it received the ACH payment, what its direct deposit availability policy says for your account, and whether an account-specific restriction applies. If the institution has no record of the payment, ask your employer or payroll administrator when it was submitted and whether the account details were correct.
Timing also matters for bills scheduled near payday. An ACH debit can be returned if there is not enough money in the account when it posts. And if an advance is repaid from the next paycheck, ask what fees apply and what happens if that deposit is late or smaller than expected. Those are separate questions from when ordinary direct deposit funds become available.
ACH rules can change. Nacha, which sets rules for the network, has announced a funds-availability rule for non-same-day credit entries with a September 18, 2026, effective date. As of August 8, that date is still ahead. For a paycheck due now, the clearest explanation remains a short sequence of facts: when payroll sent it, when the bank received it, and when your account terms say you can use it.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


