










Credit card rules can sound more immediate than they are. A late-fee rule adopted in 2024 was later vacated, while rewards terms remain tied to each card account. For cardholders, the distinction matters: a rule that was proposed or adopted but did not take effect does not automatically change a statement or rewards balance.
The Consumer Financial Protection Bureau’s 2024 rule would have lowered a regulatory benchmark for certain late fees. A court vacated that rule in April 2025, leaving the earlier framework in place. The change that was announced is not the same as a change that cardholders can count on seeing in their account.
Rewards are a separate matter. The late-fee rule did not set points-earning rates, redemption values, or rewards expiration policies. Those details are described in the terms for each account, and the effect of any future policy change would depend on what is adopted and how an issuer applies it.
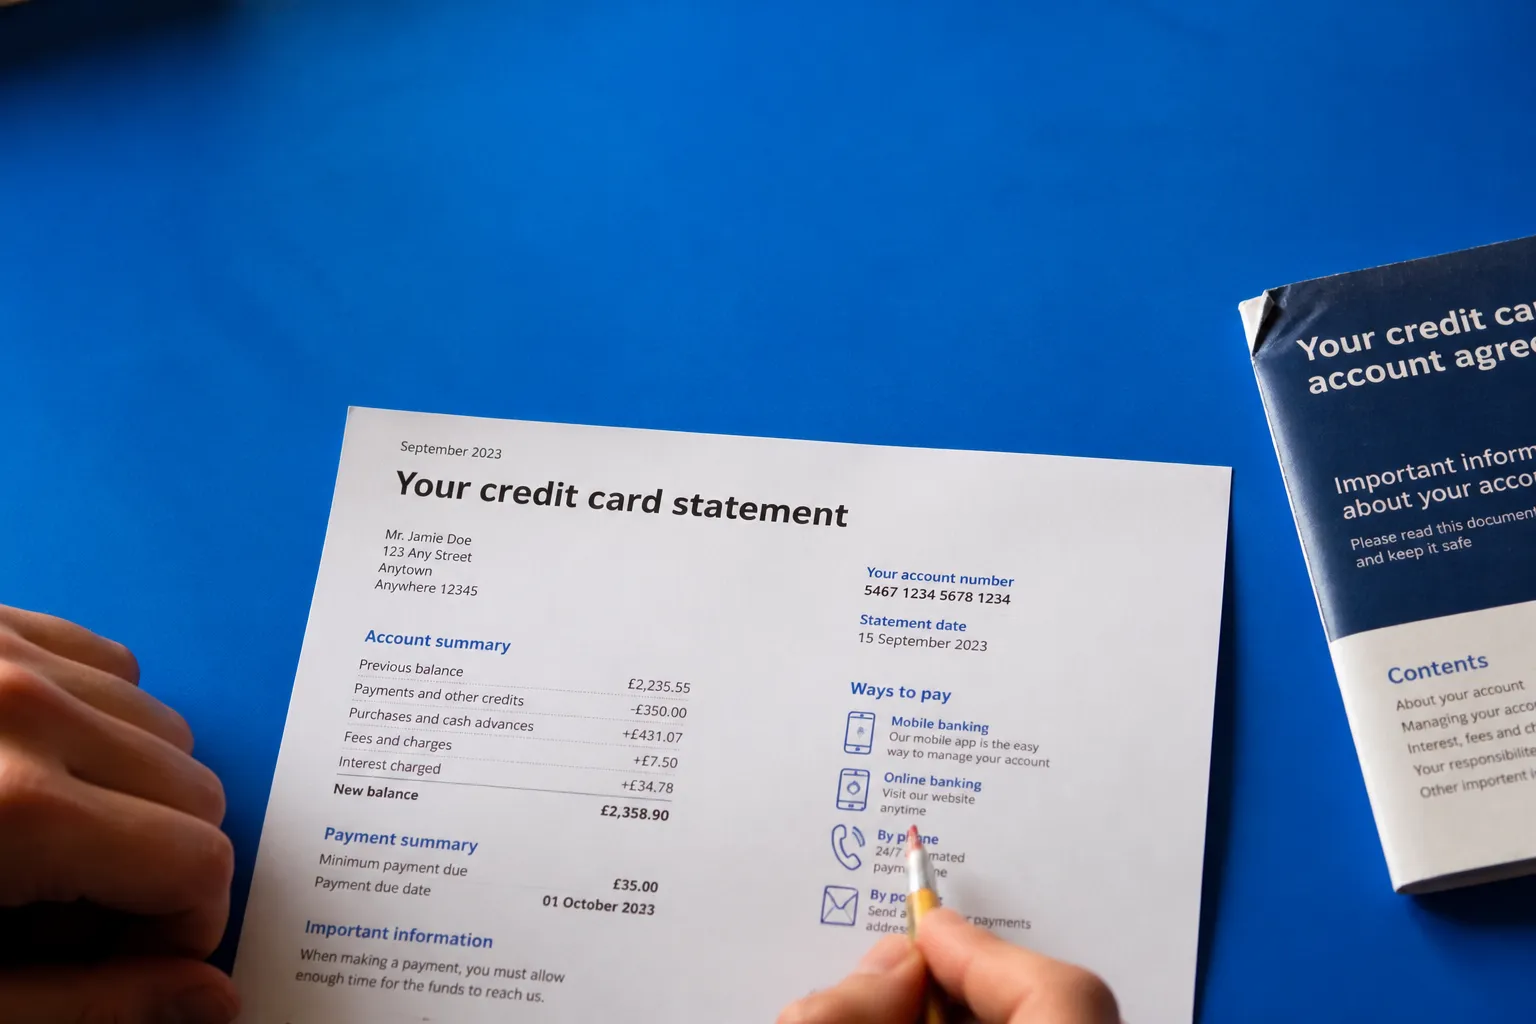
That makes the practical check fairly simple. A recent statement shows the fee an issuer actually charged, while the card agreement and rewards terms explain the rules for that account. Neither a past proposal nor a headline about a possible policy shift replaces those documents.
What happened to the late-fee rule
In March 2024, the CFPB issued a final rule that would have reduced the Regulation Z safe harbor for late fees at larger card issuers to $8. The safe harbor is a regulatory benchmark: an issuer charging within it would generally not need to separately justify the fee based on its costs. The rule compared the new amount with earlier benchmarks of $30 for a first violation and $41 for later violations. Those comparison amounts do not establish what every issuer currently charges.
The rule also would have stopped annual inflation adjustments to the safe harbor and capped late fees at 25 percent of the required minimum payment. The CFPB estimated that the rule could save consumers about $10 billion a year. That estimate described the rule as written, not savings that cardholders should expect after it was vacated.
Banking trade associations challenged the rule, arguing that the agency exceeded its authority under the CARD Act. The CFPB later stopped defending it, and the parties agreed to vacate it as part of a settlement. A court order vacated the rule on April 15, 2025. The CFPB’s credit card penalty-fees page provides agency information about the rule, while later accounts of the case describe the challenge and settlement.
What a vacated rule means for a statement
Vacating the rule means the 2024 changes did not take effect. It does not mean that all late fees disappeared, or that every card issuer charges the same amount. The earlier regulatory framework remains in place, and an account’s agreement and disclosures show the issuer’s terms. A safe harbor is not a required fee or a promise that a particular amount will appear on a bill.
To understand a charge, compare the fee shown on the statement with the fee terms in the card agreement. Check the date and circumstances associated with the charge, too. The agreement may distinguish among types of fees or describe when a fee can apply. If the statement and agreement seem inconsistent, contact the issuer to ask how it calculated the charge. This is a way to clarify an account, not a prediction about how a regulator or court would resolve a dispute.
It is also useful to separate a fee rule from a card’s other costs. The 2024 rule addressed late fees. It did not change interest rates, annual fees, or the rewards earned on purchases. A headline about one category should not be read as a change to every term on an account.
Why rewards are a separate question
Rewards programs are governed by their own terms. Those terms explain the current earning and redemption rules, and they are the relevant place to look for information about changes to a specific account. A late-fee regulation does not itself set how many points a purchase earns or whether a reward can expire.
It is possible for policy debates about card payments to raise questions about rewards, but a possibility is not a confirmed change. A claim that a policy might affect rewards does not establish that a law has passed, that a regulator has issued implementing rules, or that an issuer will revise its program. The available fee-rule history offers no basis for predicting a particular card’s future rewards terms.
For a current account, read the rewards section separately from the fee section. Look for the rules on earning, redemption, expiration, and how the issuer describes changes to the program. Keep the version of the terms that came with the account, and check updated disclosures when the issuer sends them. That gives a cardholder a concrete way to tell an existing program rule from speculation about a future one.
What to keep an eye on
The main takeaway as of November 20, 2025, is that the 2024 late-fee rule is not in force after the April court order. The rule’s proposed $8 benchmark and related changes should be treated as history, not as the current fee schedule for every card. The amount that matters for an account is the amount and conditions in its current disclosures.
For updates, start with the CFPB’s official materials and the Federal Register, where agency rules and notices are published. News coverage can help explain a development, but the underlying agency notice or court order is the best way to check what it actually does and when it applies. Until a change is formally adopted and effective, a discussion or proposal is not a new account term.
For day-to-day clarity, keep the latest statement, card agreement, and rewards terms together. The statement records what happened on the account. The agreement explains the applicable fee terms, and the rewards document explains the program. Those are three different records, and checking the right one can answer many routine questions without treating an old rule or a future possibility as a current change.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


