










You fill out the form and press submit. Then you wait. Behind that pause is a review, and federal sources describe parts of it clearly. They leave other parts out. This guide covers what is documented, marks the gaps, and explains your rights if the answer is no.
What Happens When You Apply
A credit application usually triggers a hard inquiry. That is a request by the lender to look at your credit report so it can decide whether to approve you. The Consumer Financial Protection Bureau (CFPB) ties hard inquiries to decisions about eligibility for credit.
Hard inquiries can affect your credit score. Most scoring models look at how recently and how often you apply for credit. The sources used for this article do not say how long an inquiry stays on a report. They also do not say how long it affects a score. So do not trust any specific number you hear without a source behind it.
A soft inquiry is different. Soft inquiries include prescreening, employment screening, and a lender or insurer reviewing an account you already have. Your own request for your report is also soft. According to the CFPB, these do not affect your credit scores and are visible only to you.
Your Credit Report and Score in the Decision
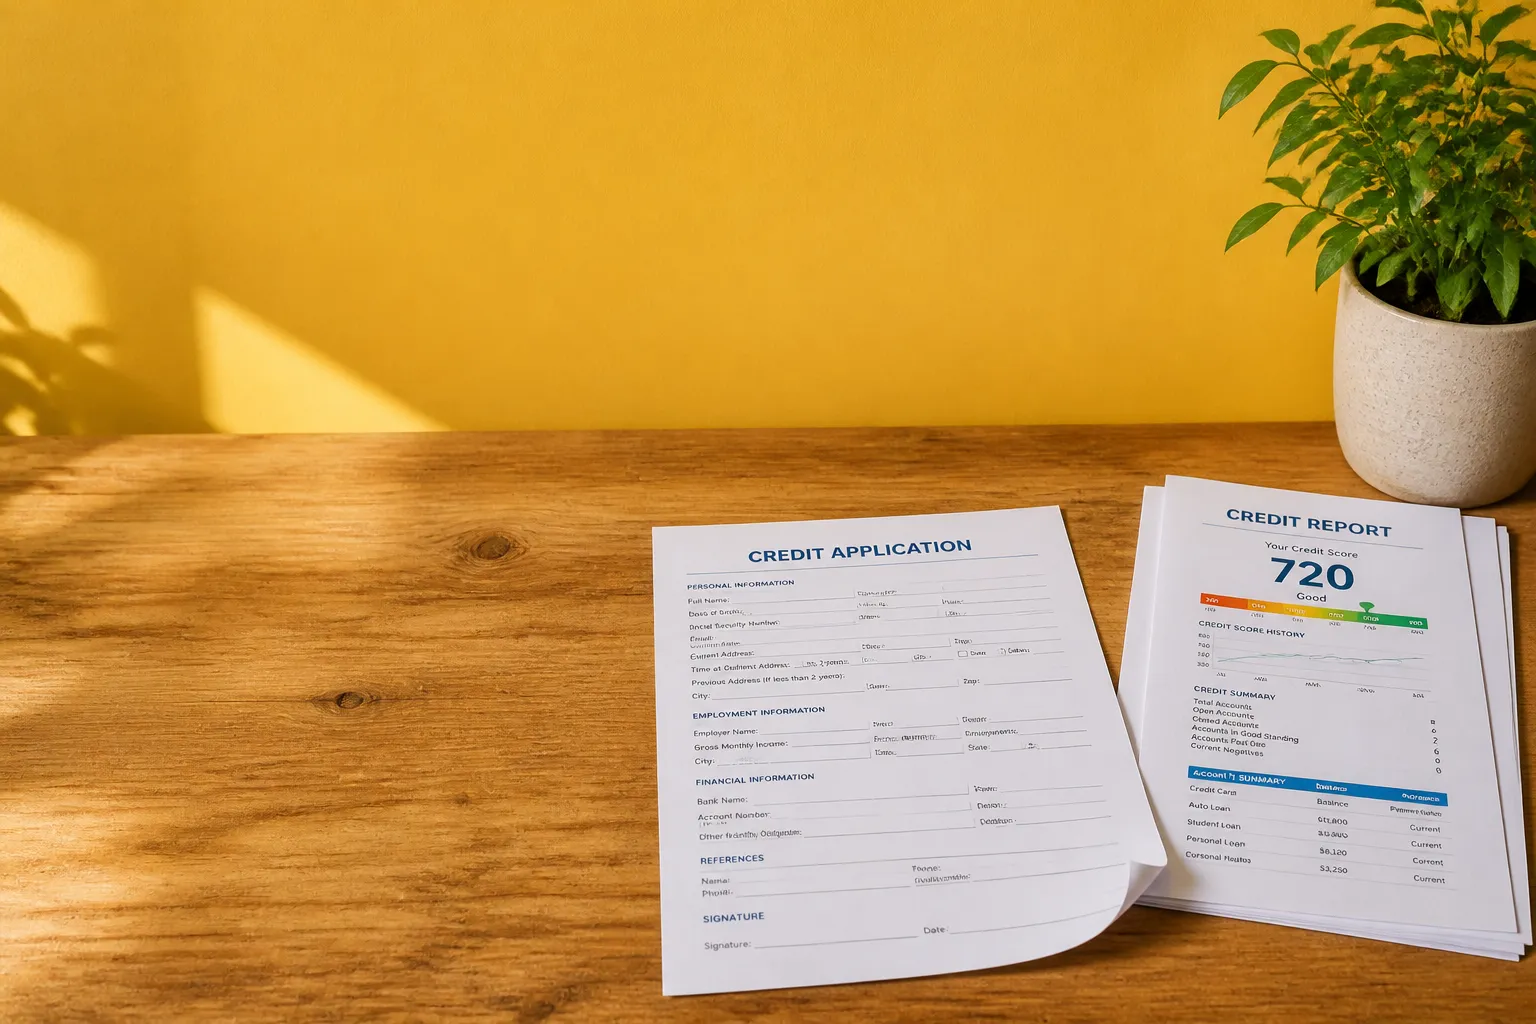
Your credit report is one input a lender may use. The public sources here do not say it is the only one, and they do not lay out how a lender weighs income, debt, or other factors. No formula is documented in them, so this article offers none.
What the sources do cover is the paper trail after a denial. If a lender turns you down based on your report, it must give you the numerical credit score it used. It must also give the key factors that affected that score. Those two items tell you what the lender saw.
Two laws sit behind this. The Equal Credit Opportunity Act (ECOA) and the Fair Credit Reporting Act (FCRA) both require a lender to tell you about adverse action. That is the formal term for a denial or other unfavorable decision. The notice must state the specific reasons, or tell you that you may ask for them.
Regulation B, found at 12 CFR Part 1002, carries out ECOA. Section 1002.6 covers rules for evaluating applications. The Regulation B page available for this article showed only its table of contents, so the rule text itself is not summarized here.
If Your Application Is Denied
Read the notice slowly. When the denial rests on your report, it must name the credit reporting company, with its address and telephone number. It must also explain how to correct mistakes or add information so the report is more complete.
Two deadlines matter. You can ask for the reasons for the denial within 60 days of the notice. You can also get a free copy of the report the lender used within the same 60 days. Write both dates down.
If something looks wrong, here is the dispute path from the CFPB:
- Contact the credit reporting company that supplied the report.
- Contact the company that furnished the information, meaning the one that reported it.
- The credit reporting company must investigate and correct any errors it finds.
The sources stop short in a few places. They do not say how long an investigation takes. They do not say what to do if it fails to settle the matter. The text available cuts off before it explains the right to add a statement to your file, though the CFPB indicates you generally have options if you still disagree. Check the CFPB page directly for those details.
Questions to Ask and Ways to Check Your Reports
After a denial, a few plain questions can help:
- Which credit report and score did the lender use?
- What key factors affected that score?
- Which credit reporting company provided the report, and how do I request my free copy within 60 days?
You have the right to review your credit reports once a year, and doing so does not affect your scores. Since the COVID-19 pandemic, the nationwide credit reporting companies have offered weekly access on request. Before you make a request, ask whether it counts as a hard or soft inquiry and whether it could touch your scores.
One more gap. The sources do not explain how prequalification differs from a full application. They do not say whether prequalification uses a hard or soft inquiry. Ask the lender before you start, and read the regulator materials yourself. This article is education only, not personal financial advice.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


