Look closely at your receipt the next time you leave a checkout counter. Many shoppers spot a small extra fee tacked onto their total, listed under labels like processing fee, non-cash adjustment, or convenience fee. Store clerks often explain that this extra charge simply covers credit card merchant fees, or they tell you that the register is set up to give cash discounts. In many stores, that explanation confuses two distinct pricing practices that state laws handle in very different ways.
A surcharge adds money to a transaction purely because you hand over a credit card instead of paying with currency. A cash discount cuts the price when you hand over physical dollar bills. Even when the mathematical total comes out identical, statutory frameworks do not treat them as the same mechanism. Knowing your rights at the checkout counter requires learning how regulators draw the line between a legal discount and an impermissible surcharge.
What a Surcharge Is and What a Cash Discount Is
The core distinction comes down to what the merchant establishes as the baseline price. When a retailer establishes a regular shelf price, that posted figure represents the standard benchmark. If you bring an item marked ten dollars to the counter, present a credit card, and discover your bill is ten dollars and thirty cents, the merchant has imposed a surcharge. The store increased the posted price because of your payment method.
A cash discount moves the ledger in the opposite direction. The merchant displays a standard sticker price that applies to card payments, but offers a reduced rate if you pay with paper cash. For example, a store might display an item at ten dollars and advertise that customers paying in cash receive a 3 percent discount, paying nine dollars and seventy cents. The customer who pays with a card pays the advertised sticker price, while the cash payer receives a markdown. The starting point determines the legal classification.
Because both structures can create a price gap between cardholders and cash payers, consumers often struggle to spot the difference at the terminal. Regulators focus on the framing. If the card price is the posted price and cash gets a reduction, you are receiving a discount. If the cash price is the posted price and the register adds a line item for paying by card, the store is charging a surcharge.
Why State Rules Differ
Whether a merchant can tack on a card fee depends heavily on the jurisdiction where you swipe your card. State legislatures across the country have enacted conflicting statutes regarding how retailers may present their pricing structures to the public. As tracked in a National Conference of State Legislatures summary, 11 states and Puerto Rico had enacted statutes prohibiting credit card surcharges, including California, Colorado, Connecticut, Florida, Kansas, Maine, Massachusetts, New York, Oklahoma, and Texas.
In contrast, the same legislative review highlighted ten states and Puerto Rico that had explicit statutory language permitting merchants to offer discounts for non-card payment. Several states appeared on both lists. This overlap demonstrates why checkout rules are not a simple binary question. A state statute might strictly ban surcharges while simultaneously protecting a merchant's right to offer cash discounts. In those jurisdictions, a posted cash discount remains legal even where a checkout surcharge is unlawful.
State statutory frameworks continue to shift, and historical summaries do not capture every recent update across all fifty states. Consumers who want to verify the exact rules governing register fees in their community should consult their state attorney general or local consumer protection bureau rather than relying on static tables.
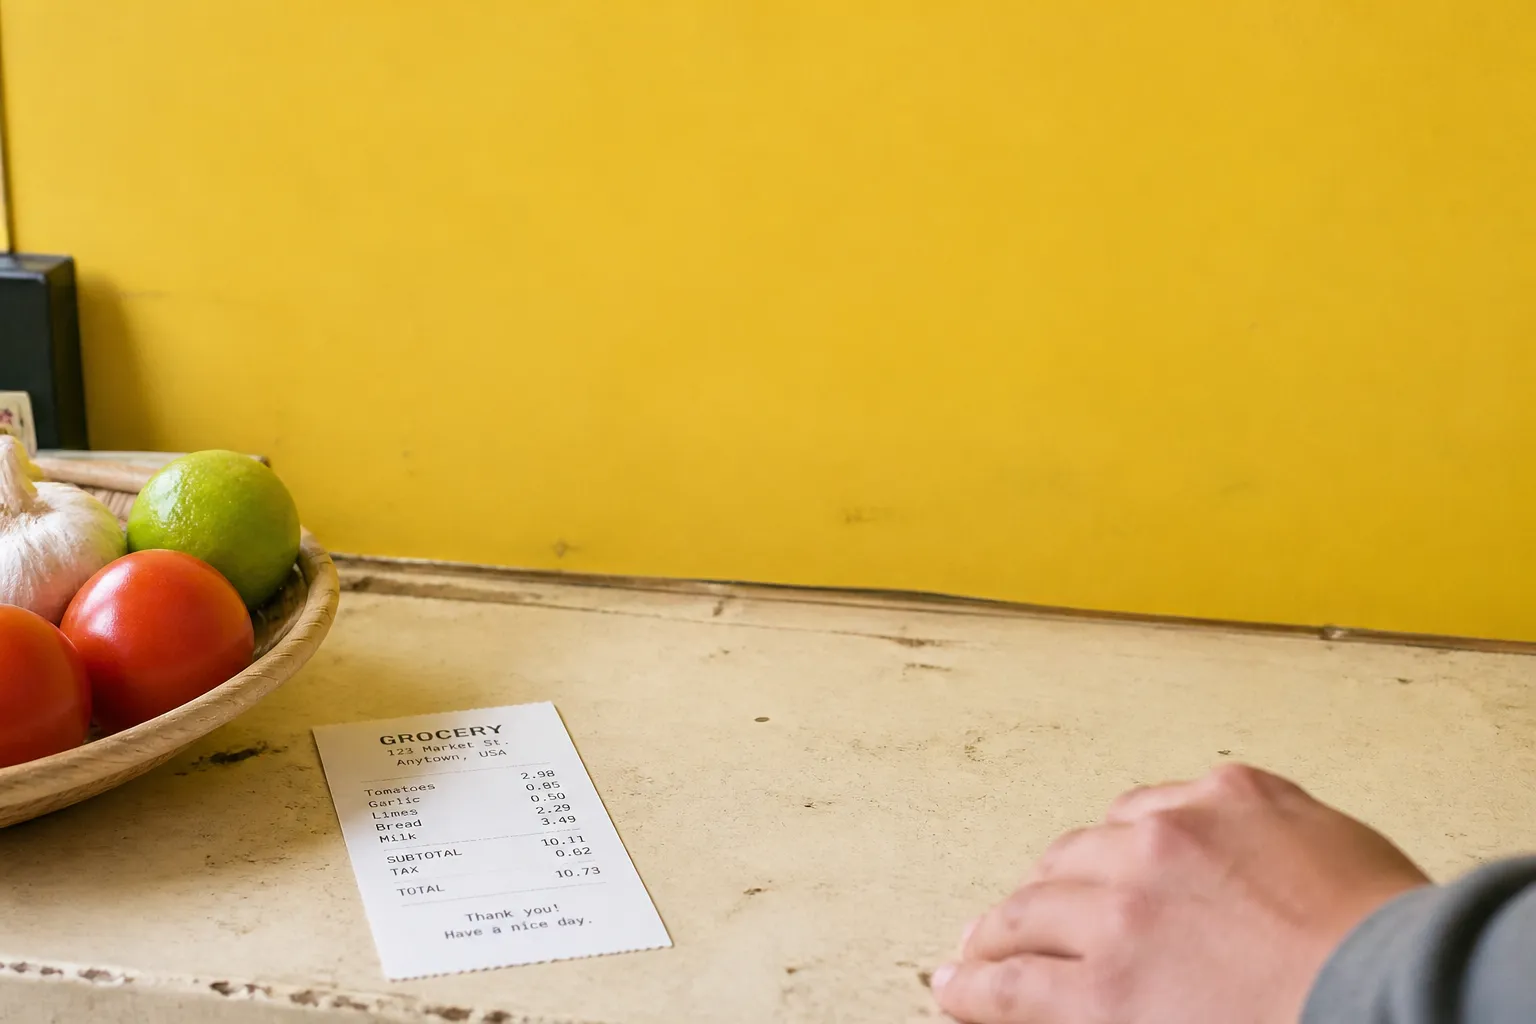
How to Read the Receipt and the Price
You can identify whether a charge is an unlawful surcharge by comparing the shelf tag with the itemized register slip. If the card total exceeds the price displayed on the shelf, and the merchant accounts for that difference by generating an extra line item, you are facing a card fee. If the store posted two prices side by side on the shelf, or posted the card price as the primary rate, the register math aligns with cash discount models.
Pay strict attention to the wording on the receipt. Retailers frequently rename these charges to avoid using the word surcharge. You might see a charge entered as a transaction fee, an administrative fee, a processing fee, or a non-cash adjustment. According to official Connecticut guidance, changing the name does not change the legal reality. A mandatory add-on applied to cardholders remains a surcharge regardless of the creative label printed on the slip.
Regulators look for specific compliance methods. In Connecticut, state regulators recognize two primary ways for merchants to offer non-card incentives legally. The first method is posting clear signage stating that a cash discount applies to all listed rates, such as a posted notice that listed prices are discounted 3 percent for cash buyers. The second compliant method is dual pricing, where the business displays both the cash price and the credit card price directly on the product or price display. Gas stations routinely employ dual pricing, and the law mandates this clarity when stations offer different tiers for cash and credit. If a receipt contains unclear charges, ask the manager to explain how their posted prices correspond to the line items.
Government Fees and Other Gray Areas
Statutory prohibitions on card surcharges do not apply universally to every public interaction. When you pay an administrative fee, fine, or property tax to a public agency, you will often notice a percentage fee added to your card transaction. Under regulatory frameworks like the one in Connecticut, government agencies, municipalities, and local court systems are often permitted by statute to pass payment processing costs directly to the payer.
These public-sector fees cover administrative costs for items like vehicle registrations, tax settlements, and court fines. Because municipal offices do not operate under the same commercial profit-and-loss models as standard retail shops, legislatures frequently create explicit exceptions for civic payments. If your town hall charges an extra two dollars to process a card payment for a municipal permit, that fee typically complies with municipal finance rules.
Intermediaries can complicate this balance further. For instance, Connecticut rules note that when an independent state marshal steps in to collect delinquent municipal taxes, the marshal may have legal authority to add separate service fees. At the state level, specific rules also target merchant-issued cards. In Minnesota, a distinct statutory rule prohibits a merchant that issues its own retail card from surcharging a customer who pays with that private card rather than cash or check. These localized exceptions mean you cannot assume one checkout rule applies everywhere.
Court Challenges and Open Questions
The rules governing card fees have remained a legal battleground for over a decade. In 2016, a preliminary antitrust settlement between major payment card networks, prominent card issuers, and nationwide retail groups granted merchants broader latitude to introduce card surcharges to offset processing fees, subject to settlement terms. However, that contractual agreement did not override state-level statutory bans that protected consumers at checkout.
State bans have faced recurring constitutional challenges centered on commercial speech rights. In California, a federal district court declared the state surcharge ban unconstitutional in Italian Colors Restaurant v. Harris, prompting an appeal. Around the same time, the United States Supreme Court agreed to hear Expressions Hair Design v. Schneiderman, a dispute challenging New York's surcharge prohibition. The New York challengers argued that banning surcharges while permitting cash discounts regulates how prices are communicated rather than the underlying economic transaction.
Litigation over payment disclosures and merchant rules continues to evolve across federal and state court systems. Existing guidance does not resolve every checkout scenario, such as how individual states treat convenience fees on online platforms, debit card transactions routed as credit, or private dispute procedures after a consumer pays an improper surcharge. If you suspect a merchant in your community has charged an improper register fee, bring the documentation directly to your state attorney general or an attorney to review the facts under current state law.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.