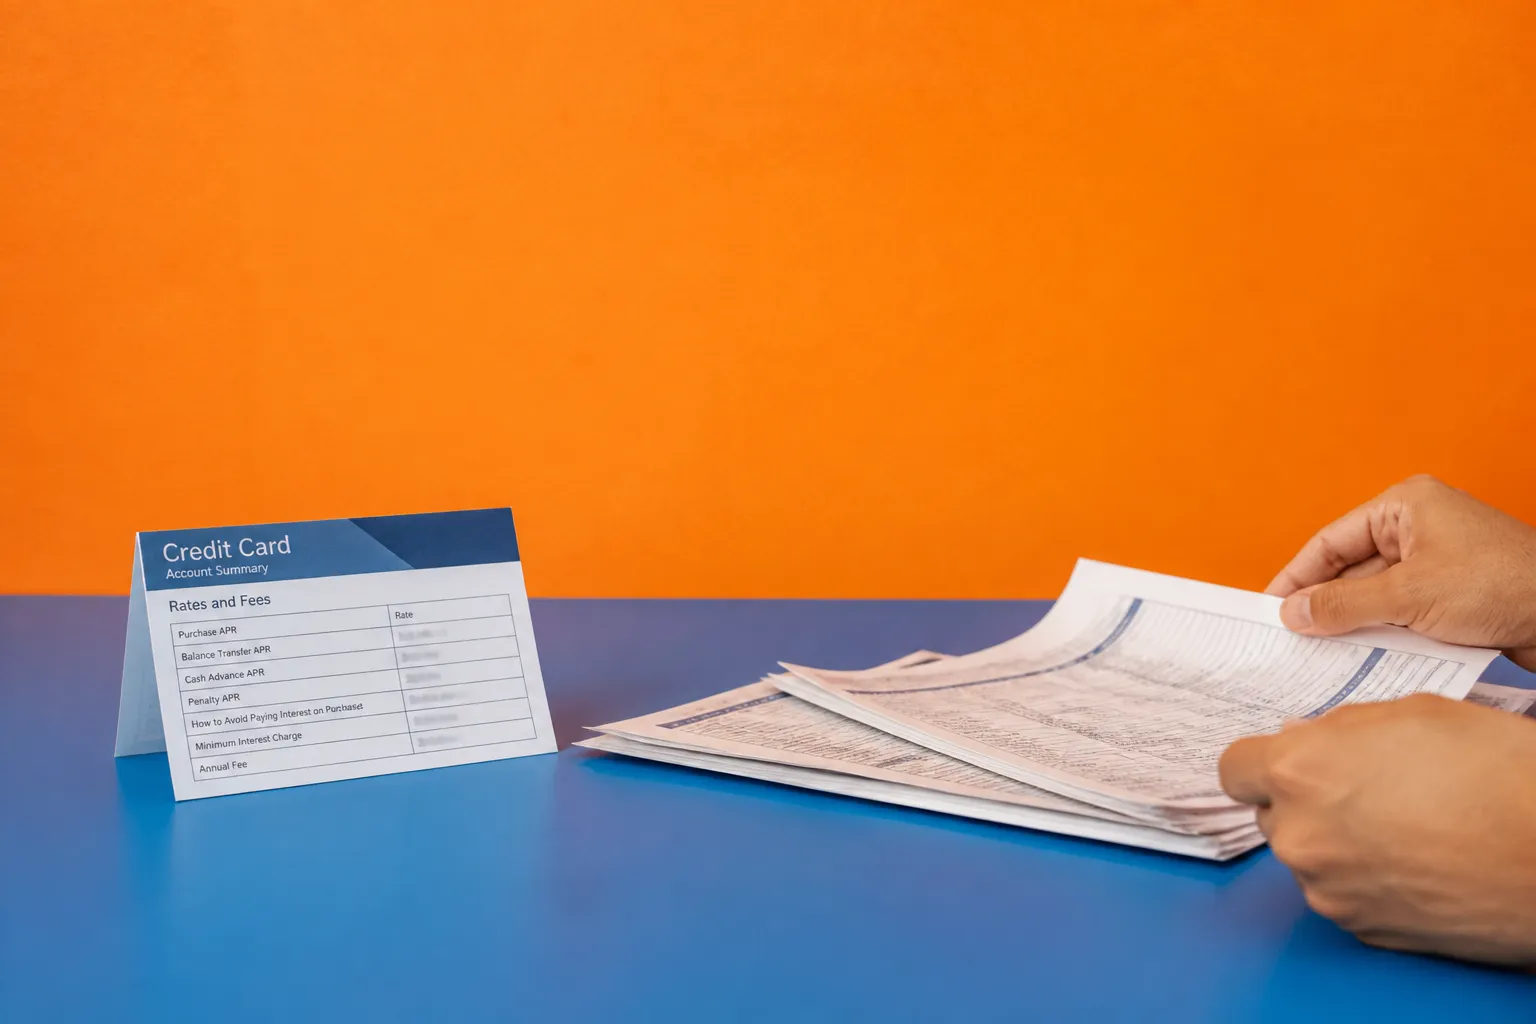
Open a credit card offer and you will often find a small table near the fine print. People call it the Schumer box. It is a standardized chart of key terms, and it exists so offers can be compared side by side. This article does not reproduce that chart. The sources behind it are the federal rule's table of contents and a cover page, not the full text. So we will walk through where the rules live and how to use them as a map.
Where the APR disclosure rules come from
The main rule is Regulation Z. It is the Truth in Lending rule, found at 12 CFR Part 1026. The Consumer Financial Protection Bureau (CFPB) publishes it. It covers two kinds of credit. Open-end credit, like a credit card, can be used again and again. Closed-end credit, like many loans, is borrowed once and repaid on a schedule.
APR means annual percentage rate. It is the yearly cost of borrowing, shown as a percentage. The rule decides how it must be presented.
The regulation is split into subparts, which are groups of related sections. General rules run from 1026.1 to 1026.4. Open-end credit runs from 1026.5 to 1026.16. Closed-end credit runs from 1026.17 to 1026.24. Miscellaneous rules run from 1026.25 to 1026.30. Home mortgage special rules run from 1026.31 to 1026.45. If you know the groups, you can find the right page fast.
One limit matters here. The supplied sources do not list the exact items the Schumer box must show. I will not guess at them. For the primary text, go to the CFPB's Regulation Z page: 12 CFR Part 1026 on consumerfinance.gov.
Which sections govern credit card disclosures
Think of a card's life in stages. Each stage has its own section.
- Section 1026.6 covers account-opening disclosures. These are the terms the issuer must give you when the account is opened.
- Section 1026.7 covers periodic statements. These are the bills that arrive over time.
- Section 1026.12 covers special credit card provisions.
- Section 1026.16 covers advertising for open-end credit.
Two more sections deal with how the APR is built. Section 1026.4 defines the finance charge. That is the cost of credit, and it feeds into the APR rules. Section 1026.14 explains how the APR is determined for open-end credit. Section 1026.22 does the same job for closed-end credit, so it is a different set of rules. Do not mix them up.
Section 1026.26 covers the APR in oral disclosures. That matters when someone describes terms by phone or in person.
What applies at the application and solicitation stage
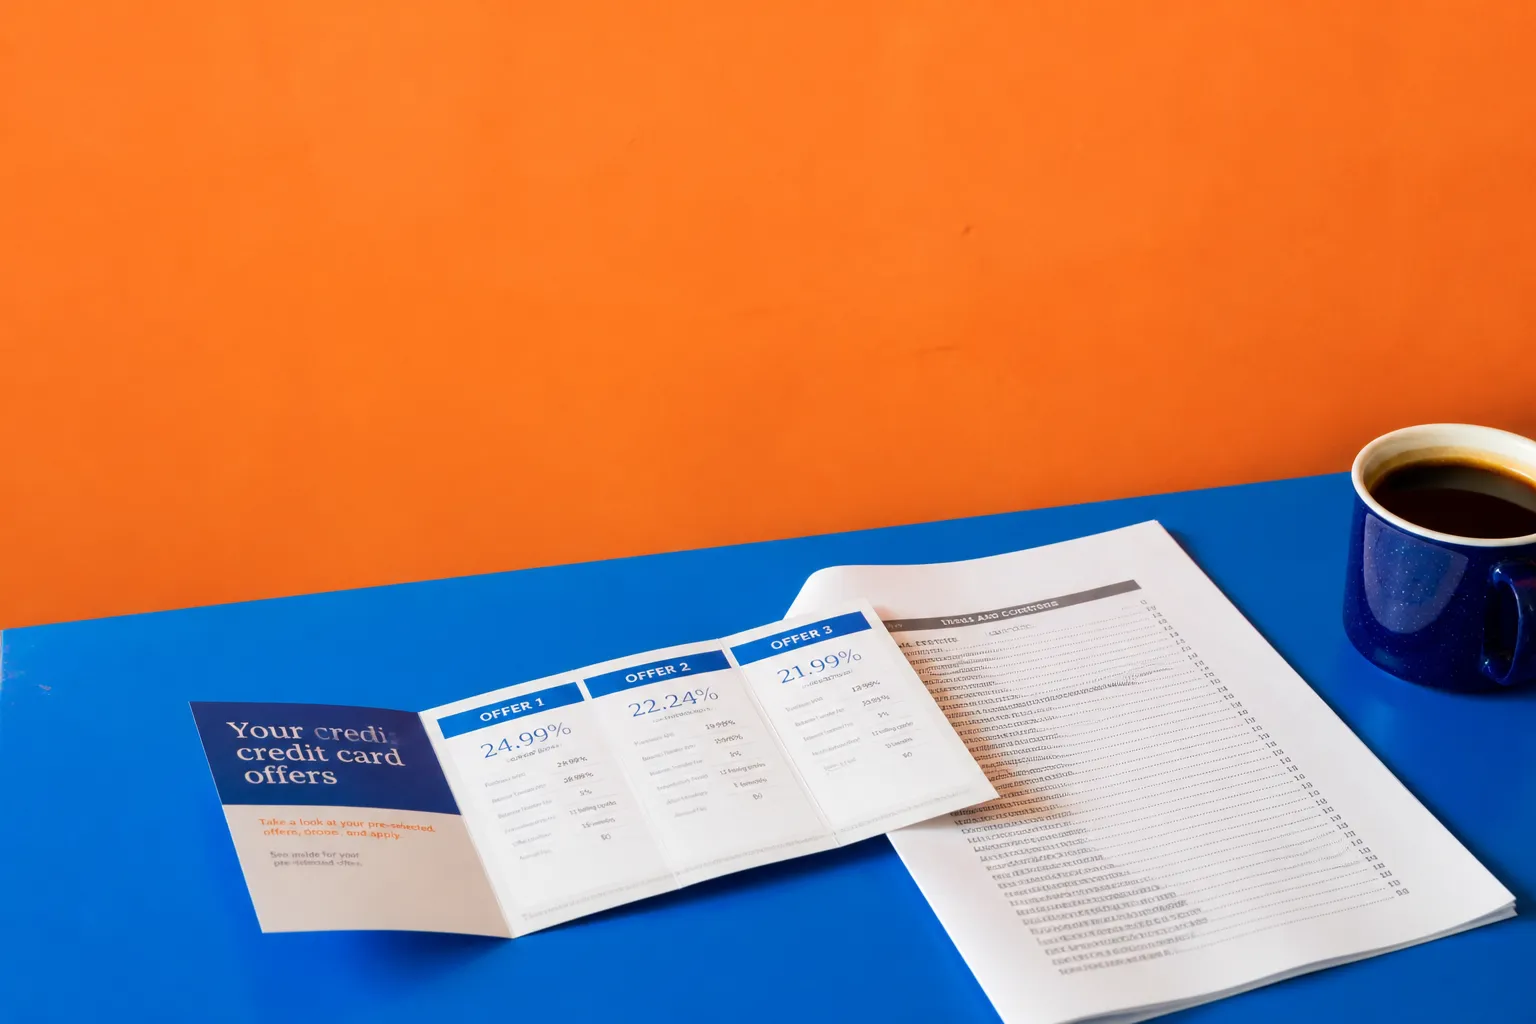
If you are comparing offers, Section 1026.60 is the one to know. It covers disclosures in credit and charge card applications and solicitations. A solicitation is an offer sent to you, such as a mailer. The CFPB posts the section here: Section 1026.60 on consumerfinance.gov.
A simple habit gives you two checkpoints. First, compare the rates and fees in an offer against what Section 1026.60 addresses. Second, once an account exists, compare the terms you receive against Section 1026.6. If the two stages disagree, you have noticed something worth asking about.
These checks have a limit. They do not tell you which card suits you. They only show whether the disclosed terms follow the federal format and whether the stages line up.
Questions to ask and what the sources cannot answer
Keep two questions handy. Does the APR in the offer match the account-opening disclosure under Section 1026.6? Are the fees and rates in the solicitation consistent with Section 1026.60? A mismatch is worth raising with the issuer. If it stays unresolved, the CFPB is the next place to take it.
Now the gaps, stated plainly. The CFPB published a final rule on credit card penalty fees in January 2024, and it is available as a PDF from the CFPB. The text supplied for this article does not include its contents. So no fee limits are stated here. Read the rule itself before drawing conclusions.
The sources also lack official CFPB guidance on reading the disclosure. They have no worked APR examples and no sample tables. They say nothing on how applying for a card may affect a credit report or score. Those topics need their own sources.
Treat the rule as a map, not a verdict. Know which section covers which stage, read the primary text, and ask the issuer when two documents do not agree.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.