










Credit card debt feels like fog. You know it is there, but you cannot see how far it goes. The Consumer Financial Protection Bureau (CFPB) says getting out of debt is possible when you know what you owe and what you can do to repay it. So we start with the knowing. Then we take the steps one at a time.
Start by Knowing Exactly What You Owe
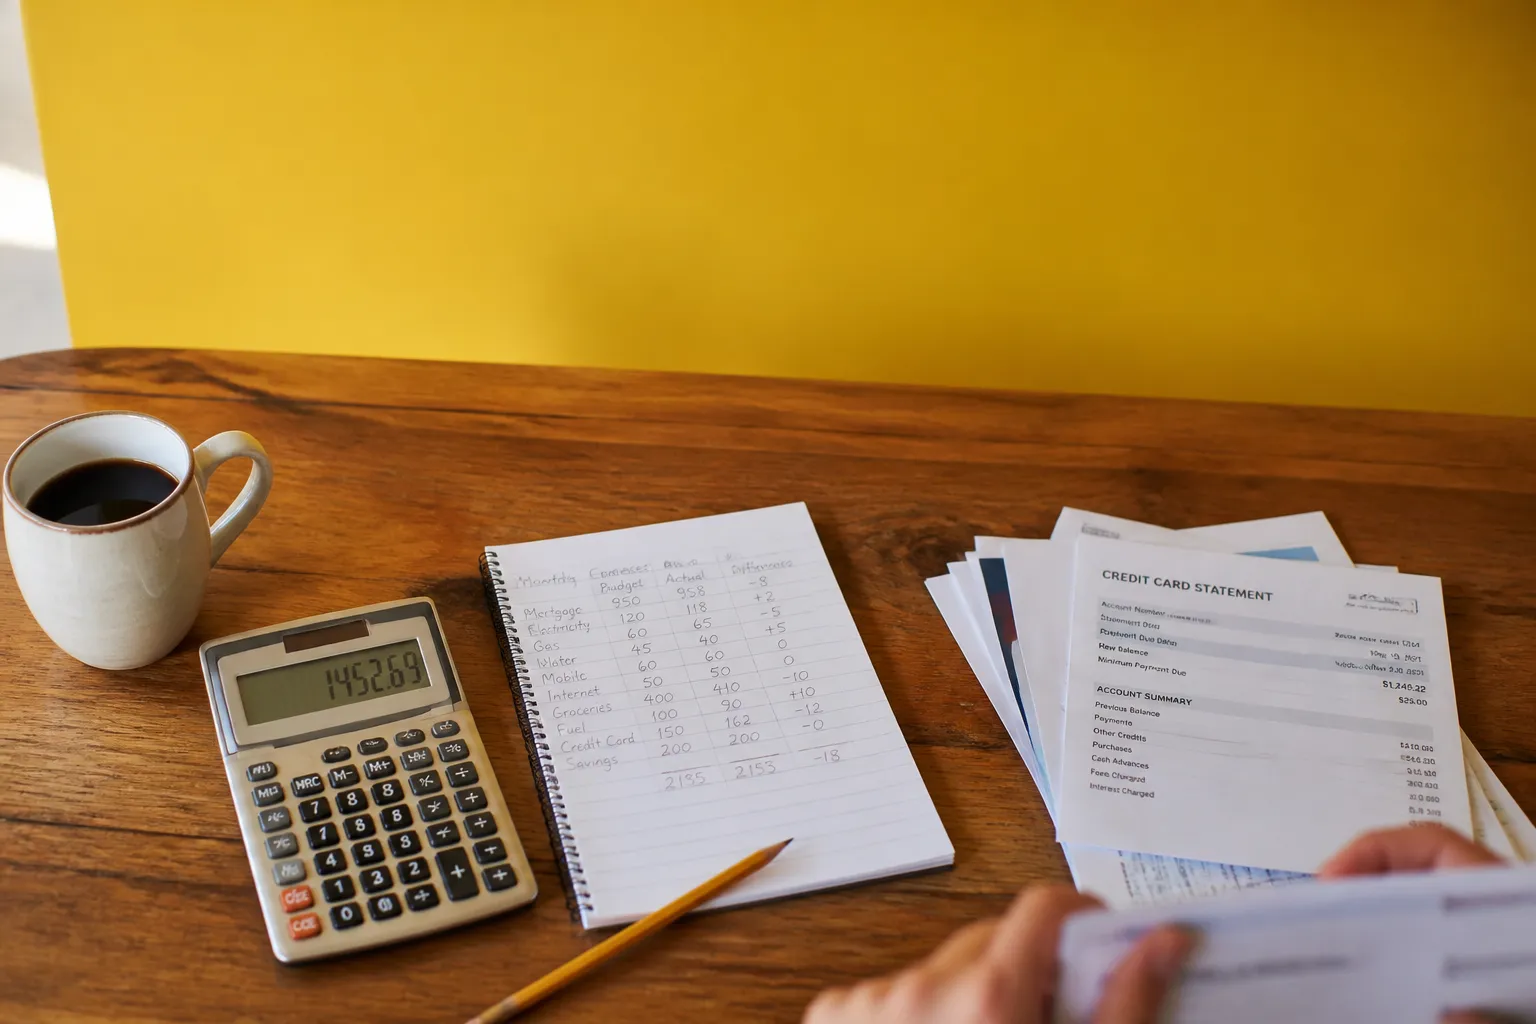
Take inventory. Write down every credit card. Next to each one, list the current balance, the interest rate, and the minimum monthly payment. The interest rate is often called the APR, short for annual percentage rate. It is the yearly cost of carrying a balance.
Now add up your monthly take-home income. Subtract your necessary expenses: housing, utilities, food, transportation, and insurance. What is left is the most you can realistically aim at debt each month. It also shows where you might cut back before you call anyone.
This full picture answers one more question. Is the problem the old balance, or are new charges still piling on? That matters. A payoff plan will have a hard time holding if the cards keep filling back up. Put the list somewhere you will see it, and update it each month as balances change.
Contact Your Card Issuer Early If You Cannot Pay
If you cannot pay a credit card bill, the CFPB says to contact the card company right away. Do it before you miss payments. The CFPB notes that many card companies will work with customers during a financial emergency.
Prepare first. Add up your income and expenses, look for costs to cut, and decide what you can afford. Then tell the representative four things:
- Why you cannot pay the minimum.
- How much you can afford to pay.
- When you could return to normal payments.
- What new payment amount you want, and for how long.
You can also ask whether the issuer will lower the minimum payment, waive fees, reduce the interest rate, or move your due date to match your pay schedule. Write down the representative's name, the date, and the terms. Keep any written confirmation.
What if the issuer says no? The agencies cited here do not lay out a step for that. Calling a nonprofit credit counselor is a reasonable next move, but that is our suggestion, not an official rule.
Choose a Payoff Method That Fits Your Situation
The CFPB describes two common methods. Both start the same way. You keep paying at least the minimum on every card. The difference is where the extra money goes.
The highest interest rate method sends extra money to the card with the highest rate first. It can save the most money in the long run. Progress may feel slow, though, because that balance may be large.
The snowball method sends extra money to the smallest balance first. When that card is paid off, you roll its payment into the next smallest. Wins come fast, which keeps many people going. The tradeoff is that you may pay more interest over time.
So pick by asking what you need more: the most savings, or quick progress. Then organize your cards by rate and balance. That gives you a payoff order you can follow each month. A single card with a zero balance, crossed off on your list, is a small and real marker that the plan is working.
Understand Consolidation and Debt Management Options
Consolidation means combining several debts into one. Two common forms are a credit card balance transfer, which is often offered at zero percent or a low rate, and a consolidation loan. The CFPB says each has important terms to review before you go ahead. It also says a consolidation loan probably will not help if you are spending more than you earn, unless you also cut spending or raise income. The sources here do not spell out rates or eligibility, so read the actual terms closely.
A debt management plan works differently, and it is not a loan. The National Foundation for Credit Counseling (NFCC), a nonprofit group, describes it as a repayment approach coordinated by a nonprofit credit counseling agency. Under such a plan, finance charges may be reduced or waived, collection calls may drop, and accounts are credited with 100% of the payments made. Enrollment steps, length, and eligibility vary, so confirm them with the counselor. No credit score result is promised either way.
Before you sign up with any credit counseling group, ask three things. Will I be charged? How much? What exactly will I get? A good counselor should tell you whether a debt management plan fits or whether another path suits you better.
Recognize Debt Relief Red Flags
Some companies prey on people in debt. The Federal Trade Commission (FTC) and the CFPB both warn about them. A debt settlement company is not allowed to collect fees before it settles or resolves your debt. An up-front fee is a warning sign.
Watch for these other signals:
- A guarantee that your debt will go away.
- Advice to stop talking to your credit card company.
- Advice to stop making your minimum payments.
- Service fees charged with little or nothing done.
- Promises to erase tax debt for "pennies on the dollar" before anyone looks at your tax situation.
Stopping payments may bring late fees, higher interest, and collection activity. If an offer sounds too good to be true, pause. Ask the company the same three questions you would ask a counselor: what it charges, how much, and what it will actually do. Then consider talking with a nonprofit counselor first, since the CFPB points to them as free or low-cost help with money management and debt.
One last note. This is general education, not advice for your situation. Your numbers are yours, and the steps above work best when you start with them.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


