










When you spot an error on your credit report, your first thought is usually how to fix it and verify that the correction went through. Many people assume that once a bureau updates a file, it automatically sends a fresh credit report at no charge. The statutory record and federal guidance do not clearly confirm that you are entitled to a dedicated post-dispute copy simply because an entry was altered. You can, however, use standard federal pathways to review your files before and after the process runs its course.
Start with the dispute, not the free report
You have the legal right to dispute inaccurate or incomplete information on your credit record. Resolving an issue generally requires contacting two parties: the consumer reporting company, such as Equifax, Experian, or TransUnion, and the company that furnished the data, such as a credit card issuer or loan servicer. Federal guidance from the Consumer Financial Protection Bureau recommends beginning directly with the reporting agency.
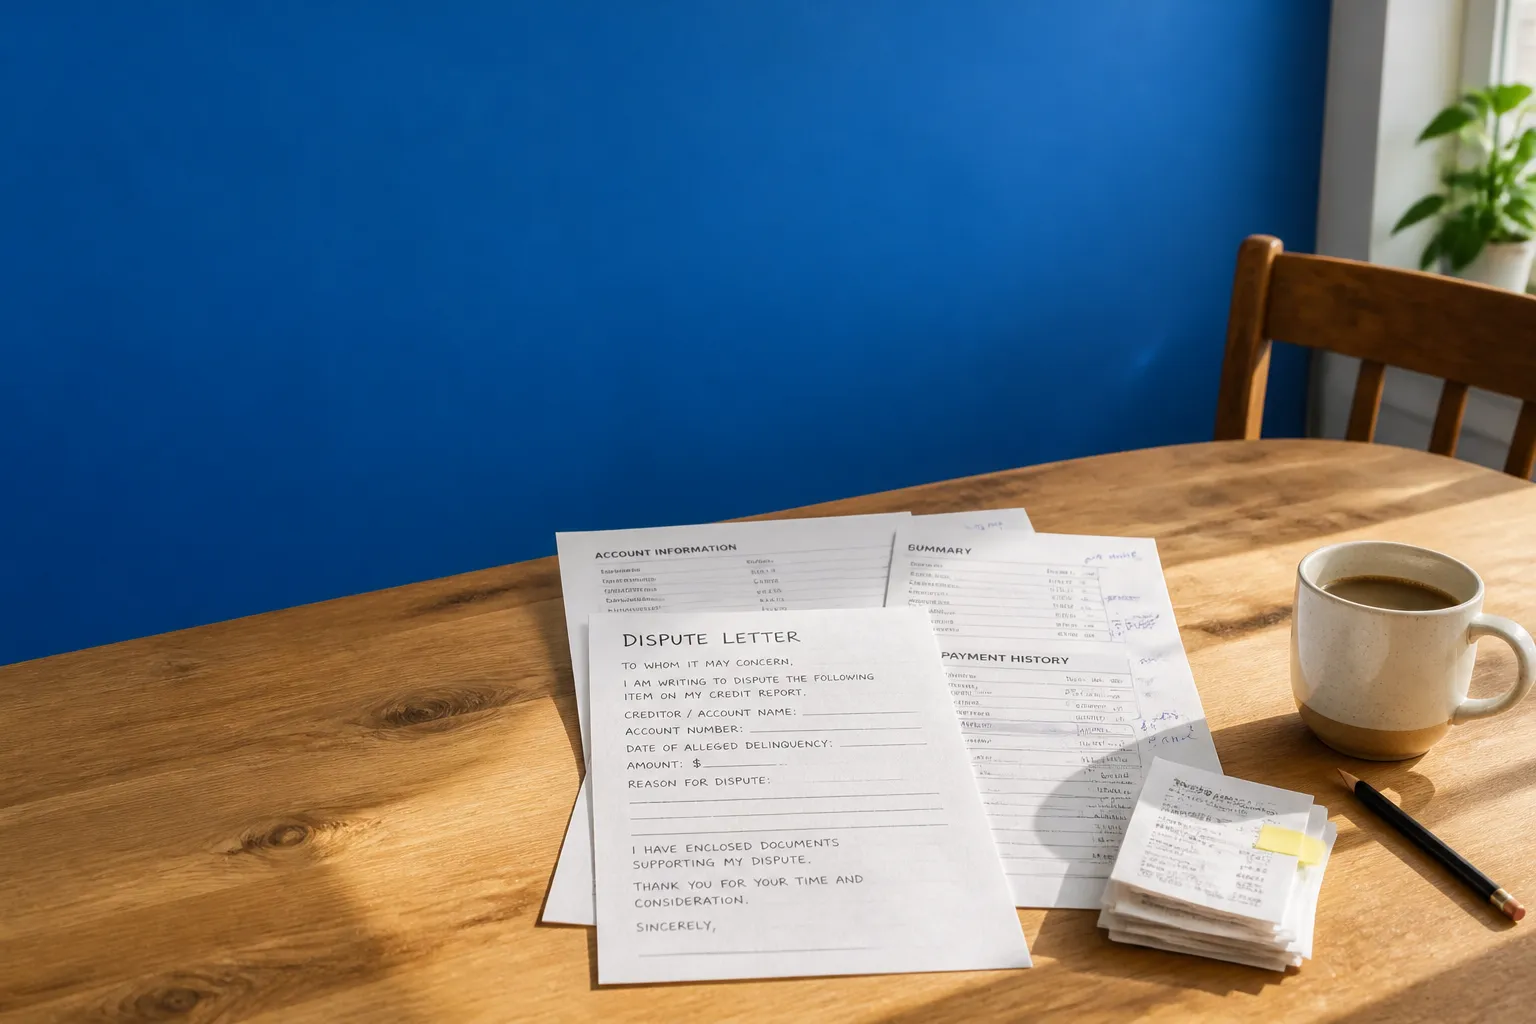
You should submit your dispute in writing. Clearly state what you believe is inaccurate and explain why the entry is wrong. Include copies of any supporting records, such as canceled checks or billing statements, but keep your original documents at home. A complete dispute letter must include your full legal name, current mailing address, and telephone number. If your file includes a confirmation number from a recent report, add that as well. List each disputed line item along with its account number, request that the agency correct or remove the item, and enclose a photocopy of the relevant section of your report with the errors circled.
Sending this packet through the United States Postal Service via certified mail with a return receipt requested gives you proof of the exact date the bureau received it. If you suspect an entry stems from identity theft rather than a clerical mistake, federal guidelines referenced on USAGov point consumers toward IdentityTheft.gov for recovery procedures. When a credit reporting company refuses to fix a documented error, consumers can file a formal complaint through the CFPB portal.
What the law says about the reinvestigation
Federal law governs how credit reporting agencies handle consumer disputes. Under 15 U.S. Code § 1681i, an agency must conduct a reinvestigation of disputed material free of charge. In most cases, the agency must finish this investigation within 30 days of receiving your notice. During that period, the bureau must either verify the entry, update the inaccurate information, or delete the item from your file.
This 30-day window can be extended by up to 15 calendar days if you send supplementary information relevant to the dispute while the initial review is underway. That extra time does not apply, however, if the bureau discovers that the disputed data is incomplete or inaccurate, or if the furnisher fails to verify it within the initial 30 days. In addition, the agency must notify the business that provided the data within five business days of getting your dispute notice, forwarding all relevant facts you supplied.
While the statute lays out these strict deadlines for the review itself, the statutory text provided does not explicitly mandate that an agency deliver a new, free credit report solely because a dispute changed your file. That specific entitlement is not confirmed in these legal sources. Readers should not assume that a clean investigation notice will automatically arrive with an entire free report attached.
Getting a free report you are entitled to
Even if a completed dispute does not trigger a special post-investigation report, you still have dependable ways to inspect your files. Under federal rules detailed by the CFPB, you can pull a free copy of your credit report from each of the three nationwide credit bureaus once every 12 months. The nationwide bureaus also allow you to request free online reports once a week through the federally authorized site, AnnualCreditReport.com.
Consumers have three authorized ways to order these statutory disclosures:
- Order online at AnnualCreditReport.com, where you can inspect records from one, two, or all three bureaus in one session.
- Call toll-free at (877) 322-8228 to place an automated phone request.
- Complete the standardized Annual Credit Report Request form and mail it to Annual Credit Report Request Service, P.O. Box 105281, Atlanta, GA 30348-5281.
Use caution when searching for credit reports online. Many commercial websites claim to offer free files but condition access on purchasing monthly credit monitoring packages or insurance subscriptions. Other sites enroll visitors into recurring trial subscriptions that must be canceled manually to avoid unwanted charges. Ordering directly through the authorized federal clearinghouse avoids those sales pitches entirely. Checking your report through that portal after an investigation closes is an effective way to confirm that the bureau updated or removed the disputed record.
What the sources do not cover
The materials available leave several practical questions open. The statutory excerpt does not specify the precise remedies available within the dispute chapter if an agency fails to resolve an inquiry within the required 30 or 45 days. The record also omits the exact visual format of the written results notice that agencies send at the end of a reinvestigation.
Furthermore, federal guidance does not promise any specific credit score result if an account is removed or altered. A score depends on many underlying elements across an entire profile, and removing one inaccurate entry might not alter a score in a predictable way. If an agency fails to respond to your written submissions within the statutory deadlines, submitting an administrative complaint through the CFPB remains the primary recourse documented in the available record. For questions involving complicated financial damages or potential litigation, consumers should consult an attorney rather than relying on general educational summaries.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


