










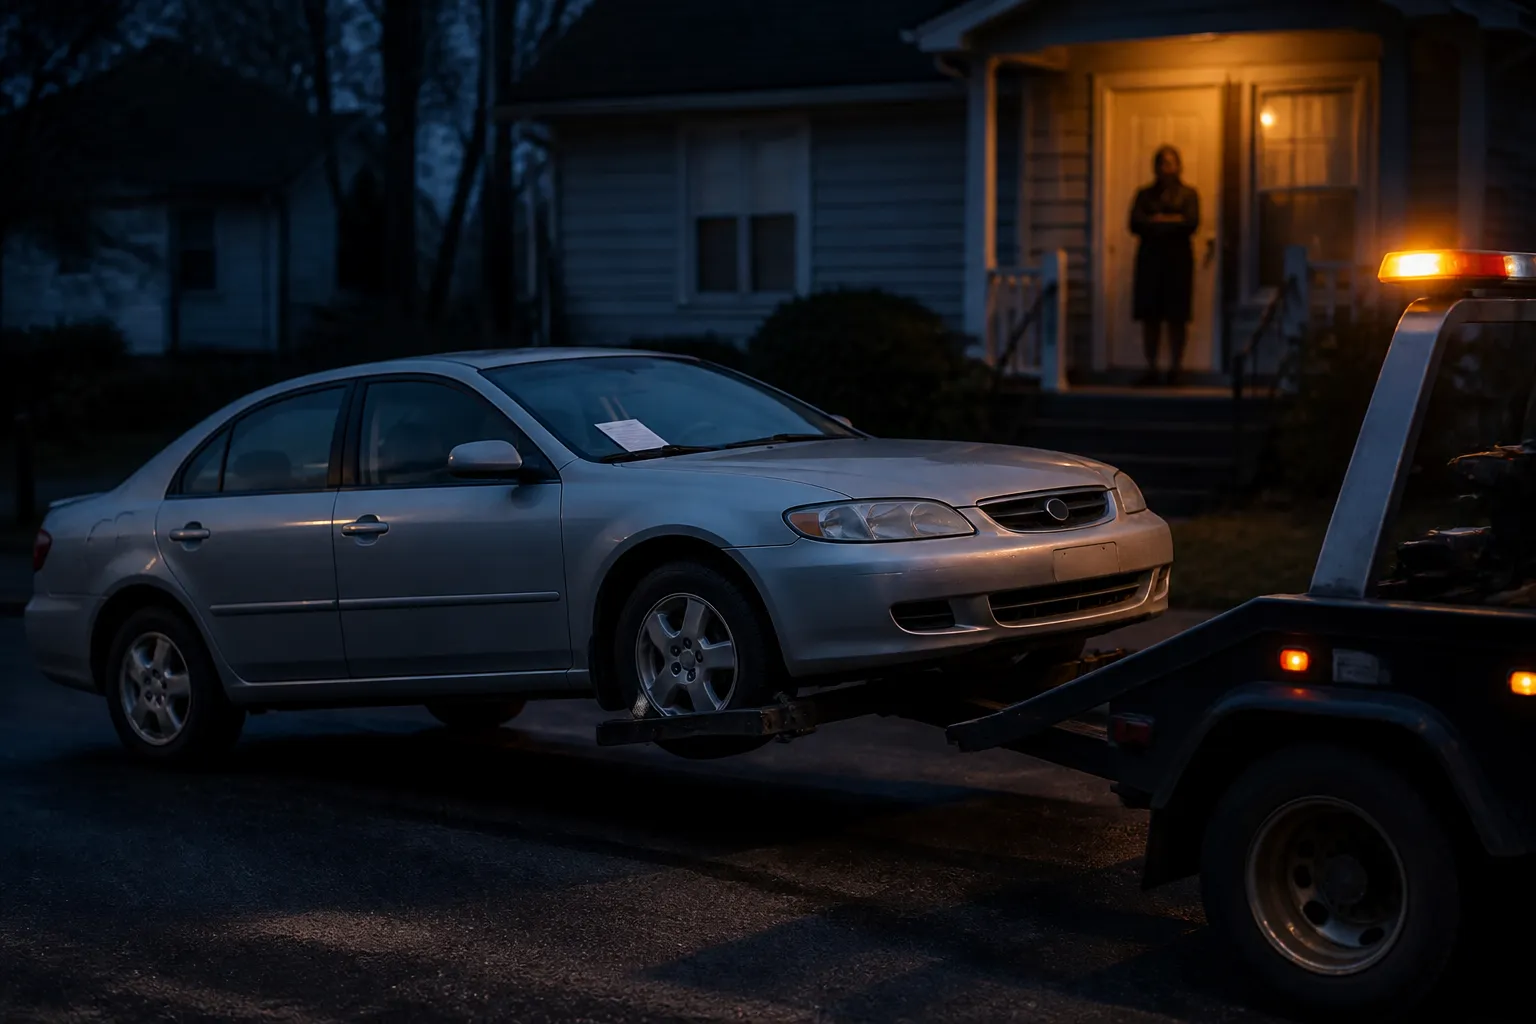
What a Repossession Is and Why It Happens
When you purchase a vehicle using financing, you enter into a loan agreement that grants the lender a legal security interest in the car. According to legal standards outlined by the American Bankruptcy Institute, this lien gives the creditor rights over the vehicle until the loan is fully satisfied. If a borrower defaults on the loan contract, the lender is empowered to exercise those rights to recover its financial interest.
A loan default most commonly begins when a borrower misses a scheduled payment, but the exact point of legal default depends on the written contract terms and governing state law. Once a default occurs, a creditor generally has three primary pathways under the loan contract: it can launch repossession proceedings directly, sell the underlying contract to a third-party assignee, or seize and sell the vehicle at auction. Crucially, the contractual obligation to repay the underlying debt remains intact even if the car is no longer in your possession.
How Repossession Takes Place Under State Law
Once an auto loan enters default, a creditor or its designated agent may enter your property to seize the vehicle without providing advance notice. This aspect of auto finance often catches borrowers off guard, as agents can lawfully take a car directly from a driveway, an open parking lot, or a public street.
Whether a creditor must provide a preliminary warning depends heavily on jurisdiction. In many states, state law permits a lender to repossess a vehicle immediately following a missed payment without issuing a prior warning or obtaining a court order. Other states require lenders to issue a formal notice of default, detailing missed payments and providing a specific timeframe for the borrower to catch up. Borrowers should always inspect their specific state commercial codes rather than assuming uniform rules across the country.
State law across the country imposes a strict restriction on repossession activity: the lender or its agent may only take the car without "breaching the peace." Under standard legal definitions, a breach of the peace occurs if an agent uses threats, applies physical force, opens a locked garage or fence without permission, or continues the seizure after a borrower actively resists on site. However, borrowers must also note that once a creditor formally announces its intent to repossess, hiding the vehicle from the recovery agent is legally prohibited.
Federal Protections and Statutory Rights
Certain borrowers receive heightened protections under federal legislation. Active-duty servicemembers are protected under the Servicemembers Civil Relief Act (SCRA) for vehicle contracts entered into prior to entering military service. Under the SCRA, if a servicemember paid a deposit or at least one loan installment before starting active duty, a creditor generally must secure a formal court order before repossessing the vehicle, even after repeated missed payments.
The SCRA does not erase or forgive the underlying auto debt. Unpaid installments can still generate late fees, result in adverse credit reporting, trigger collection activity, or lead to civil lawsuits. Servicemembers who experience an unlawful repossession without the required court order should contact a military legal assistance office immediately.
If you believe an auto repossession was conducted in error or executed unlawfully, contact your lender or servicer right away to register your dispute. If the servicer fails to resolve the issue, you can file an official complaint with the Consumer Financial Protection Bureau and evaluate potential legal remedies in court. If a repossession agent breached the peace during the recovery, contacting local law enforcement can document the incident, creating an official record that may support legal defenses or claims to reduce the overall debt owed.
Costs, Fees, and Broader Financial Impact
The financial consequences of auto repossession extend far beyond losing access to transportation. After a vehicle is seized, the borrower remains legally responsible for paying the remaining loan balance alongside repossession fees, storage fees, and legal costs. If the vehicle is sold at auction for an amount lower than the total debt owed, the remaining balance is classified as a deficiency balance, which the creditor can legally demand that you repay.
A repossession, alongside the missed payments that preceded it, damages your credit file and can be reported to national credit bureaus. Official federal disclosures do not specify an exact numerical score reduction or a fixed timeline for credit impacts, meaning individual financial outcomes will vary.
The auto finance sector has seen elevated rates of default in recent years. In a published analysis examining accounts from 2018 through 2022 across nine major auto lenders, the CFPB reported that vehicle repossession rates at the end of 2022 surpassed pre-pandemic levels within a $1.64 trillion auto loan market. The CFPB further observed that lenders increasingly rely on third-party intermediaries, known as forwarders, to manage recovery operations, a structural shift that frequently inflates consumer fee burdens.
Key Statutory Gaps and Action Steps
Federal guidance and standard summaries leave several critical operational details unaddressed, as specific rules depend heavily on local state statutes. Key areas requiring local verification include:
- The precise notice timelines lenders must fulfill before and after seizing a vehicle.
- Whether state law grants a right of redemption allowing borrowers to reclaim the vehicle by paying past-due amounts or the full balance.
- The legal procedures governing how repossessed cars must be advertised and sold at auction.
- The precise rules requiring lenders to inventory and return personal belongings left inside the repossessed car.
To fill these procedural gaps, review consumer resources provided by your state attorney general or state consumer protection office. If you are experiencing payment hardship, reaching out to your lender or servicer early before default occurs remains the most direct way to inquire about available payment arrangements. This article provides educational overview details on consumer rights and regulatory guidelines; readers facing active repossession disputes should consult a qualified legal attorney or a non-profit credit counselor for personalized assistance.
Please seek a professional. This article is general information, not financial, tax or insurance advice. Please seek a licensed financial, tax or insurance professional about your own situation.


